Best Stocks to Buy for Rising Interest Rates This Fall
The Fed just raised interest rates for the first time since 2023, with another hike in 2026 likely. Let's talk about the best stocks for rising interest rates.

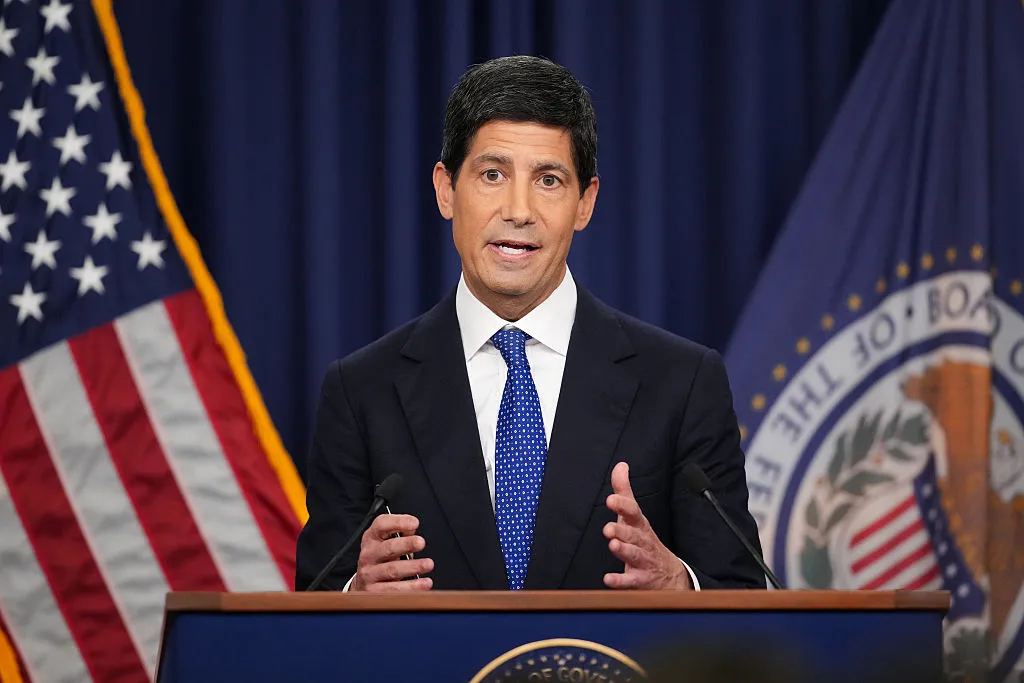
Amid persistent inflation exacerbated by tariffs and war, the world's most important central bank just raised interest rates for the first time in three years. Markets expected an increase of 25 basis points, and that's what they got from the September Fed meeting.
After a brief official policy statement and another meandering post-meeting press conference, how to invest for fall rate hikes by the Fed is a live question.
Before he took questions from reporters, Fed Chair Kevin Warsh said a unanimous decision underscores the Federal Open Market Committee's commitment to price stability.
So something you might like to know right now is where to look for the best stocks to buy for rising interest rates.
The target range for the federal funds rate is now 3.75% to 4.00%. Already, price action in the fed funds futures market, as tracked by CME FedWatch, shows a 50.9% probability of another 25-basis-point rate hike at the October 27-28 Fed meeting.
Indeed, as Warsh reiterated once more, "I said we will deliver stable prices."
Stocks were volatile during the Fed chair's third post-FOMC meeting press conference, reflecting what substance he shared, as well as the equally persistent geopolitical uncertainty the committee cited in its statement.
It also reflects potential pain from increased borrowing costs for consumers and businesses. At the same time, Warsh would argue that stable prices are better for everybody, most of all consumers, in the long run.
In fact, some stocks supported by resilient business models will be insulated from rate-related disruptions and might even benefit from higher interest rates.
As always, identifying a list of the best stocks to buy for rising interest rates or any other factor means defining your criteria.
Generally speaking, large-cap stocks with the heft to survive through the business cycle, backed by strong balance sheets, are best equipped to handle the landscape when rates are rising. The key factor is the flexibility, as opposed to the sheer size. And we can find that up and down the market cap scale.
For example, financial stocks do well in rising-rate environments because their net interest margins have more room to expand. And, right now, energy stocks with efficient operations are well positioned to profit from higher commodity prices, after years of sector-wide efforts to reduce debt and focus on sustainable growth.
Bottom line, there are different paths to opportunity amid the challenges that come with tighter monetary policy.
Here are seven of the best stocks to buy for rising interest rates this fall.
Data is as of September 16.

Bank of America
- Sector: Financials
- Market value: $406.3 billion
- Dividend yield: 2.2%
Bank of America (BAC) is among the biggest financial institutions in the world, and right now the blue chip stock is the favorite among its "too big to fail" peers in the eyes of Wall Street analysts.
Bank of America is rated a Strong Buy by 15 analysts and a Buy by five more, while four say it's a Hold. Based on a system developed by S&P Global Market Intelligence, that works out to a consensus Buy rating.
Those analysts see BAC trading at $68.86 12 months from now, which is almost 19% above its September 16 closing price. The stock is up 10% so far in 2026, trailing a gain of 11.7% for the S&P 500.
BAC sold off even harder than other bank stocks that sank on September 14 after Bank of America CEO Brian Moynihan said at a financial conference hosted by Barclays that third-quarter sales and trading revenue would be "flat" on a year-over-year basis.
"It'll be one of the better third quarters we've ever had," Moynihan explained, "but it'll be relatively flat to last year, because last year was a big recovery from the second quarter."
Morgan Stanley analyst Manan Gosalia reiterated his Overweight (Buy) rating and his $67 12-month target price for BAC in the aftermath of Moynihan's guidance.
"We believe this is a temporary pullback," the analyst writes of BAC's greater than 5% slide on the CEO's remarks. Indeed, higher rates strengthen Bank of America's net interest income, net interest margin expansion and operating leverage story, according to Gosalia.
That's what makes BAC one of the best stocks to buy for rising interest rates.
Sponsored Content


Intercontinental Exchange
- Sector: Financials
- Market value: $86.4 billion
- Dividend yield: 1.3%
Intercontinental Exchange (ICE) is down 2.5% year to date through September 16 vs a gain of almost 12% for the S&P 500.
ICE, the ticker symbol for the company that operates the New York Stock Exchange, has also underperformed the State Street Financial Sector Select SPDR ETF (XLF, +4.7% YTD) so far in 2026.
But Wall Street is bullish, with nine analysts rating the stock a Strong Buy, another five saying it's a Buy and one calling it a Hold. That's a consensus Strong Buy rating. And a $187.29 average 12-month target price represents upside of 21.6% from here.
ICE is among the best stocks to buy for rising interest rates because higher volatility will drive more trading volume across the exchanges it operates in addition to the NYSE.
Management reported better-than-expected second-quarter results in July, highlighted by revenue growth across all of its business segments.
ICE also announced a $6 billion acquisition of fixed-income data platform MarketAxess Holdings (MKTX) that should close in early 2027.
MarketAxess supports trading for Treasury bonds and Eurobonds, as well as corporate bonds and municipal bonds and emerging market debt for more than 2,100 institutional investors and broker-dealers.
According to ICE, the combined platform will serve every segment of the fixed income market through a single, unified ecosystem.
Sponsored Content

HA Sustainable Infrastructure
- Sector: Financials
- Market value: $4.7 billion
- Dividend yield: 4.7%
HA Sustainable Infrastructure (HASI) is recognized as a financial stock under the global industry classification system (GICS) devised by S&P Global Market Intelligence. It also represents an opportunity to participate in upside from the effort to combat climate change.
HASI invests in large-scale infrastructure such as utility-scale solar farms, onshore wind parks and battery energy storage systems, as well as on-site or near-site solar and storage systems.
It also finances energy efficiency improvements such as HVAC upgrades and lighting and building controls that reduce overall energy consumption. It funds renewable natural gas (RNG), clean transportation fleets and ecological projects, too.
Founded in September 1981 and headquartered in Annapolis, Maryland, HASI completed its initial public offering (IPO) in April 2013. The stock has generated a total return of 546% since then vs 524% for the S&P 500.
Revenue and earnings are growing at double-digit rates, and HASI yields a generous 4.7% at these levels. It's well-favored on Wall Street, with nine Buy and four Outperform ratings vs three Hold ratings. The average 12-month target is $49.80, which suggests there's upside of about 37% from here.
And Mizuho analyst Maheep Mandloi reiterated his Outperform rating and raised his 12-month target price on HASI to $50 in early September, noting that "rate sensitivity remains manageable."
As Mandloi explained, 95% of HASI's debt is at fixed rates or is hedged, "while growing yields and improving debt spreads support investment-margin durability."
That's enough to make an exception for this mid-cap stock in a rising-rate environment.
Sponsored Content

Devon Energy
- Sector: Energy
- Market value: $55.7 billion
- Dividend yield: 2.5%
Devon Energy (DVN) has traded at a persistent discount to its larger peers in the oil and gas exploration and production industry, according to Stifel analyst David Deckelbaum. But there's an opportunity ahead to close that gap.
The analyst resumed coverage of DVN on September 9 with a Buy rating and a $61 12-month target price, citing stabilizing and improving capital efficiency, as well as potential asset optimization opportunities, in the aftermath of Devon's merger with Coterra Energy in May.
Deckelbaum is one of 26 analysts who rate the stock a Strong Buy or a Buy, while three say it's a Hold. An average 12-month target price of $60.43 represents upside of almost 25% from DVN's September 16 closing price.
"DVN commands one of the most attractive Delaware Basin positions in E&P and has maintained a robust return of capital profile and conservative balance sheet," Deckelbaum writes.
The analyst highlights the competitive value of Devon's deep inventory in its core areas heading into a cycle of potential asset sales. He also expects cost-cutting and streamlining efforts over the next several months to benefit the share price.
Altogether, Devon Energy is one of the best stocks to buy for rising interest rates.
Sponsored Content

Fair Isaac
- Sector: Technology
- Market value: $23.6 billion
- Dividend yield: N/A
You may recognize Fair Isaac (FICO) from its ticker symbol, which is the shorthand for consumer credit scores nationwide. The firm was founded back in the 1950s as a data and analytics company, and eventually developed a way to compile credit histories and "score" the spending and borrowing history of consumers and businesses.
Its ubiquitous FICO scores help determine not just whether someone qualifies for a credit card or a mortgage or auto loan, but how much interest they will pay.
The case for FICO as one of the best stocks for rising interest rates is based on the idea that, in this type of environment, more attention is paid to creditworthiness and credit scores.
What used to be a modest increase in borrowing costs for less-than-perfect borrowers can now become an onerous burden, and parties on both sides of loans are looking to assess and manage their credit risks. That's ultimately a good thing for Fair Isaac.
It's also worth noting that while one division of FICO is focused on this scoring business, it also provides other analytics and decision-management solutions for businesses to help them run more efficiently. In the present age, that means incorporating artificial intelligence (AI) into your operations.
And Fair Isaac is gaining traction in the AI fraud detection business. FICO is down almost 42% year to date, as markets continue to evaluate what AI means for similarly situated software stocks over the long haul.
Meanwhile, top- and bottom-ling growth remain steady. And Wall Street is still basically bullish, with 14 analysts rating the stock Buy or Outperform, six rating it a Hold and one calling it a Sell.
That's more mixed than the other best stocks for rising interest rates on our list. At the same time, their average 12-month target price of $1,440.16 is more than 45% above FICO's September 16 closing price.
Sponsored Content

McKesson
- Sector: Healthcare
- Market value: $103.1 billion
- Dividend yield: 0.4%
McKesson (MCK) provides healthcare services worldwide, including technology and financial solutions to medical facilities, as well as pharmaceutical distribution and wholesale medical supply sales.
This diversified operation has helped MCK stock largely sidestep any of the broader disruptions we've seen in the economy related to commodity inflation and rising interest rates.
The services it provides, including software for pharmacies to help manage prescriptions and the regular delivery of gloves, bandages and other staples to medical offices, have incredibly reliable sales and profits.
This reliability has helped MCK steadily set aside resources to return capital to shareholders. That includes $2.5 billion of stock buybacks during its fiscal 2027 first quarter, as well as a 15% dividend increase announced in July, making this the 10th straight year the company has raised its payout.
There's a lot of uncertainty right now, but healthcare generally is a recession-proof sector. And with the solid operations of a company like McKesson, investors looking for the best stocks for rising interest rates can have confidence that their money will be safe regardless of the ups and downs in the economy.
Wall Street likes it, too, with 14 analysts rating the stock Buy or Outperform and four rating it a Hold. Based on an average 12-month target price of $980.73, those analysts see upside of more than 10% from here.
Sponsored Content

Affiliated Managers Group
- Sector: Financials
- Market value: $8.9 billion
- Dividend yield: 0.01%
As you may have guessed by the name, Affiliated Managers Group (AMG) is a group of affiliated asset managers that offer access to mutual funds, hedge funds, institutional services and white-glove financial advice to high-net-worth individuals.
AMG is one of the top 10 publicly traded asset management firms with a book of approximately $942 billion as of June 30. Its specialty is to identify and partner with investment firms around the world that specialize in actively managed investment strategies for aggressive, ultra-rich investors, rather than participate in the "race to the bottom" on low-cost index funds built for hands-off retirees.
What also makes AMG interesting is that it is truly a network of affiliates. Its suite of "boutiques" includes offices with expertise in different areas, independent staff and strong brands in their local markets. This allows it to separate itself from the one-size-fits-all approach that many mega-managers such as Vanguard or Fidelity deploy.
And aside from the competitive advantage of its specific operations, rising interest rates generally means rising returns on firms sitting on a lot of capital.
Analysts are upbeat toward Affiliated Managers Group, too, with six of the seven who cover the financial stock rating it a Buy. Their average 12-month target price of $437.57 is almost 28% higher than AMG's September 16 closing price.
Related content
Sponsored Content
