

Retiring in 2026 means focusing on three key areas: your finances, health care and lifestyle. Even if you have a comprehensive retirement checklist, you need to start tackling critical tasks now in 2025 to ensure you're ready.
What needs your attention now? You should start by focusing on Social Security, as applying for benefits has key timing and eligibility quirks you can’t ignore. Closely related are the enrollment rules for Medicare, where properly timing your application is essential to avoid gaps in medical coverage and potential late enrollment penalties.
Here are five things that anyone planning to retire in 2026 should consider right now:
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues

Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.

1. Plan for the timing of Social Security benefits
Applying for Social Security benefits is the easy part. The hard part is deciding when to apply for your Social Security benefits and rounding up all the documents you'll need when you do.
The Social Security Administration (SSA) recommends applying for benefits three months before the month you want them to start. You'll also need to decide whether to apply online or in person at your local Social Security office.
Read: Four Things You Need to Know Before Applying for Social Security to avoid unnecessary delays or a reduction to your Social Security benefits..
Social Security birthday rule. Your birth date determines when you are eligible to apply for benefits. This matters more if you are filing early or at your Full Retirement Age (FRA). You want to be sure to observe the rule and not claim your benefits earlier than allowed or before you are eligible for your full benefit.
The Social Security Administration has some specific rules for those born on the 1st day of a month, January 1, and February 29. If you fall into any of these three categories, you will use a different date than your actual birth date to claim your benefits.
First of the month: If you were born on the first of the month, Social Security will determine your benefit (and your full retirement age) as if your birthday were in the previous month. This is the case if you were born on the first of the month from February to December, but not January.
First of January: If you were born on January 1, your birth month is December, and your birth year is the year before your actual birth.
February 29: Even though your birthday only comes once every four years, your benefits won’t be affected. So even though your actual date of birth doesn’t come every year, the month does, and the Social Security Administration counts February as your birth month.

2. Understand Medicare enrollment deadlines
This is a critical step, as missing your enrollment windows can result in lifetime penalties and delays in coverage.
- Initial Enrollment Period (IEP): Your initial enrollment period for Medicare begins three months before the month you turn 65, includes the month you turn 65, and ends three months after your birthday month. For example, if your 65th birthday is in June 2026, your enrollment window is March 2026 through September 2026.
- Special Enrollment Period (SEP): If you or your spouse is still working and has health insurance through that employer when you turn 65, you may be eligible for a SEP to sign up for Medicare after your employer coverage ends. This allows you to avoid the late enrollment penalty.

3. Create a detailed retirement budget
Before you retire, you need a clear understanding of your future income and expenses.
- Track your spending: Spend a few months tracking your current expenses to get a realistic picture of your lifestyle costs.
- Estimate retirement expenses: Some expenses will decrease (commuting, work clothes), while others may increase, such as travel, hobbies and health care. A good rule of thumb is to budget for 70% to 85% of your pre-retirement income, but this can vary.
- Assess your income streams: Tally up all potential sources of income, including Social Security, pensions, 401(k) or IRA withdrawals, and any part-time work or other sources.

4. Adjust your investment portfolio
As you get closer to retirement, your investment strategy should shift from income growth to wealth preservation.
- The "Glide Path": Financial advisers often recommend a "glide path" strategy, which involves gradually reducing your exposure to stocks and increasing your allocation to more conservative investments such as bonds and cash. The '120 Minus You Rule' approach to retirement portfolio construction is one way to approach the task of risk reduction.
- Create a Cash Bucket: Many retirees keep a cash reserve (one to two years' worth of living expenses) in a high-yield savings account or money market fund to earn interest and maintain some liquidity. This "cash bucket" can be used to cover expenses without having to sell off investments during a market downturn.

5. Plan for non-financial aspects of retirement
A successful retirement isn't just about money; it's about purpose and well-being. It stands to reason that if you want to be happy, you have to keep doing things that give your life meaning.
- Define your purpose: What will you do with your time? Will you volunteer, pursue a hobby, travel, or spend more time with family? Having a plan for this new phase of life can help you avoid a sense of aimlessness.
- Health and wellness: Plan for how you'll stay physically and mentally active. This can include everything from regular exercise to taking free classes and joining social groups.
- Test your plan: Some people even recommend a "practice retirement" by living on their projected retirement budget for a few months to see if it's sustainable.
You're close to the finish line

Don't rush through the final months leading up to your retirement, or you're likely to overlook an important deadline or apply too early for your benefits. When it comes to Medicare and Social Security, you need to be aware of how long it takes for those benefits to start to avoid gaps in your medical coverage and have enough funds to tide you over until your first check arrives.
Starting now gives you time to observe how much money you spend and fine-tune your budget before you retire. You can also start to imagine how you will spend your time after you leave the workplace. And if travel is in your future, you can leverage your newfound flexibility to lower costs and avoid seasonal crowds.
Related Content
-
 Nasdaq Hits New Highs on AI Boom Optimism: Stock Market Today
It's a relatively quiet week for earnings and economic data, as markets focus on major themes such as AI and interest rates.
-
 Who Qualifies for the New $90 Medicare Part B Rebate?
Are you getting $90 back on your Part B premiums? Here is a complete breakdown of who qualifies, who is excluded, and when payments arrive.
-
 IPO Strategy: Why Waiting to Invest Pays Off
IPOs are exciting — that doesn't mean they're bargains, and you're usually better off tuning out the hype. Here's a checklist to help you decide when to invest.


-
Who Qualifies for the New $90 Medicare Part B Rebate?
Are you getting $90 back on your Part B premiums? Here is a complete breakdown of who qualifies, who is excluded, and when payments arrive.
-
 If You're a Teacher With 2 Retirement Plans, Here's How to Use Both
Eligible education workers can contribute to 403(b) and 457(b) plans, giving them flexibility when deciding how to save and use retirement funds.
-
 Houston, We Have a Strategy: How to Treat Your Retirement Plan Like It's a (Space) Mission
What do you want your retirement to look like? Define the mission first, and the appropriate investment products will practically pick themselves.
-
 How to Give Money to Your Kids Without Setting Them Up for Failure
Helping them out is cool, but the best gift is teaching them how to manage money, be realistic about their standard of living and learn to stand on their own.
-
 Wills vs Trusts: How to Decide What's Right for Your Family
Does your estate plan need a will, a trust or both? Understanding how these tools work, and what your family needs, will help you make the right choice.
-
 Will Your Stock Portfolio Wreck Your Legacy? Check Your Estate Plan for These Instructions
Without explicit instructions for stocks in your estate plan, your heirs may end up selling everything for simplicity or because they're mired in conflict.
-
 How Playing Dead Can Maximize Your Investment Returns (Seriously)
Don't ignore the markets entirely, but don't let your emotions control decisions based on headlines and volatility. Here's what to do instead.
-
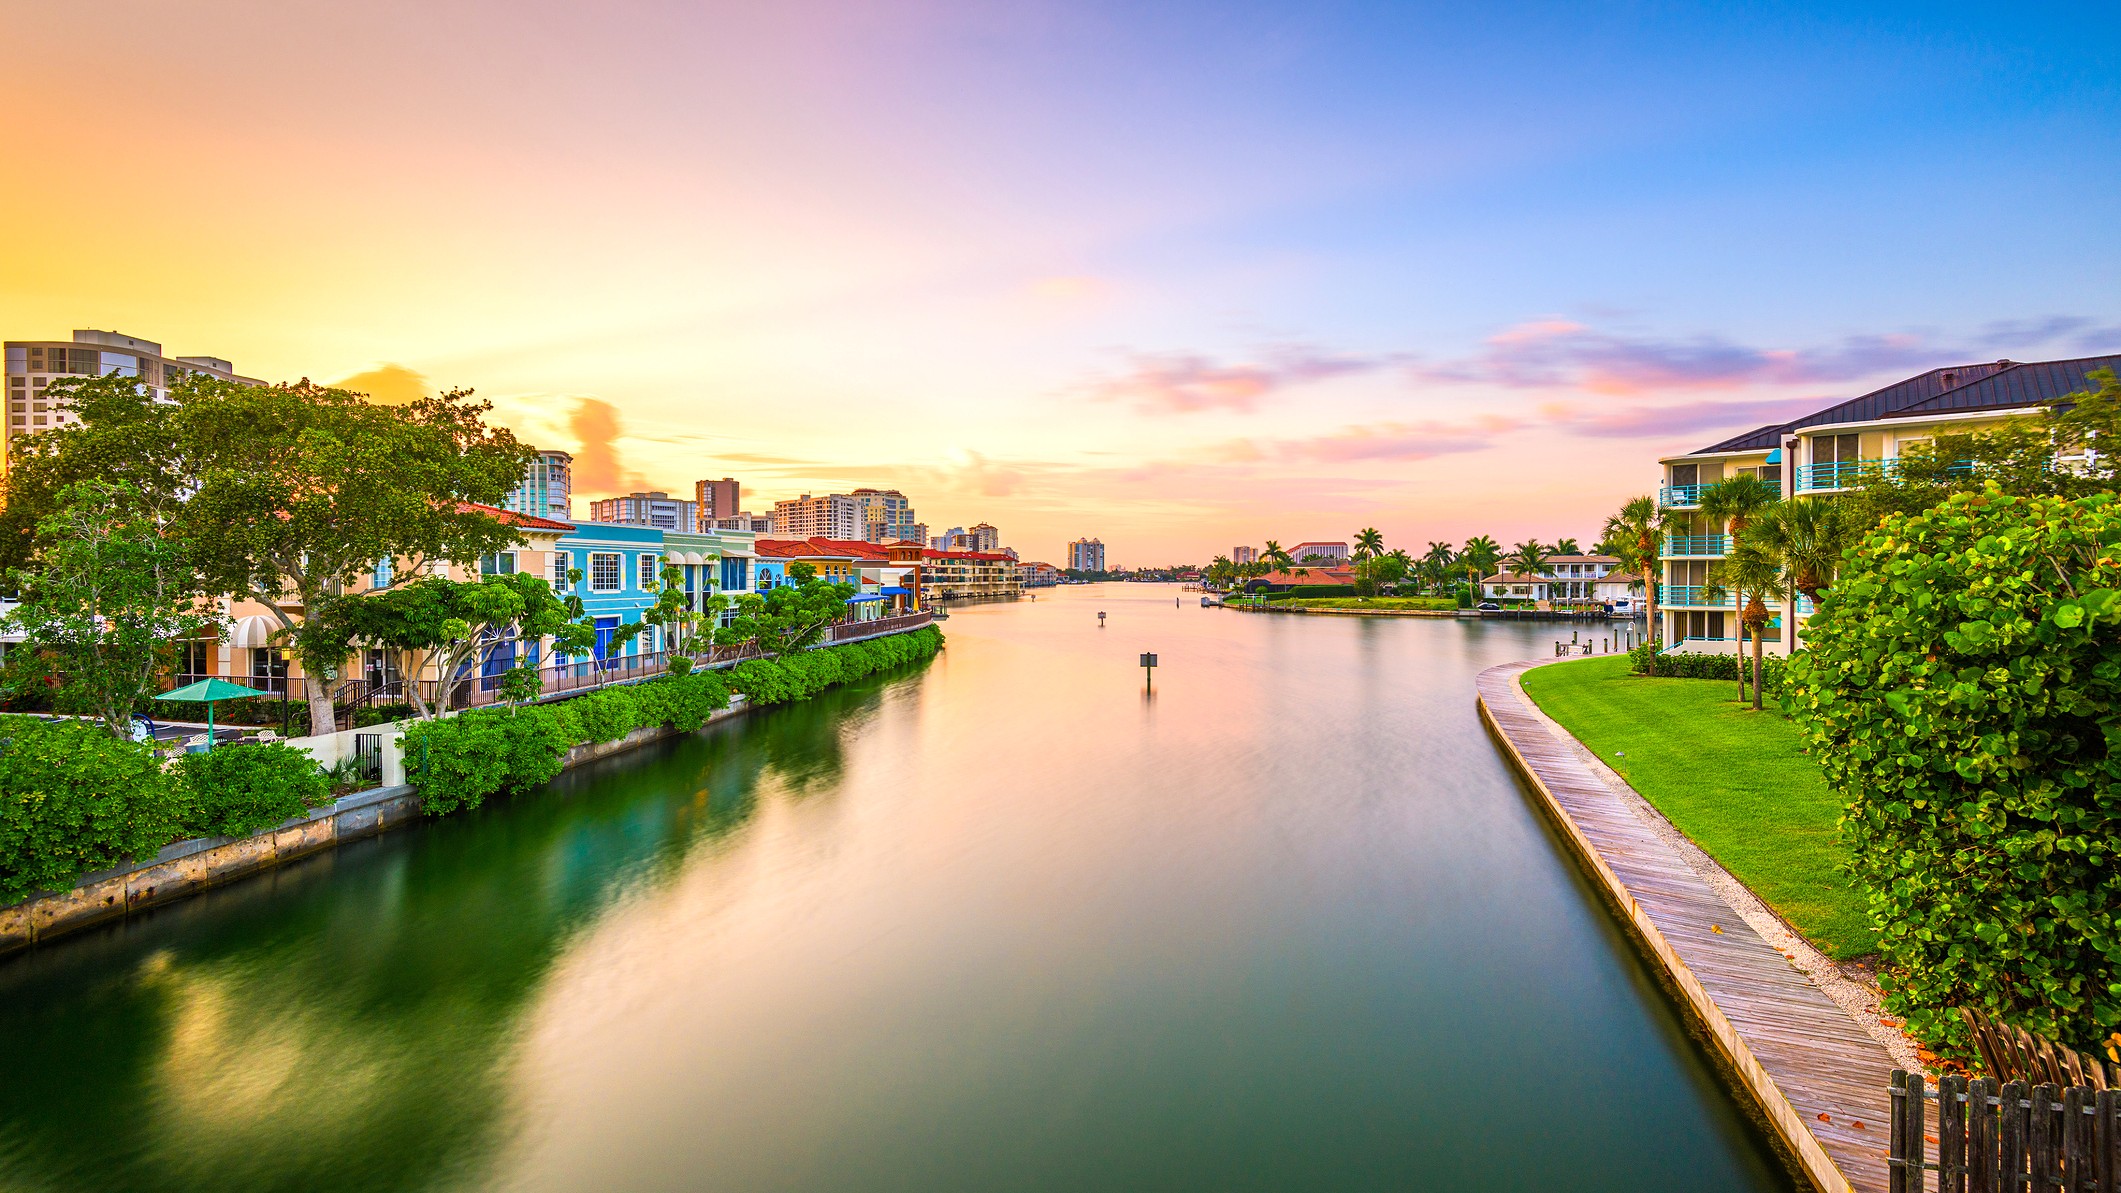 Would You Rather Retire in Naples, FL, or Palm Springs, CA?
Coastal tradition or desert cool? We break down the real cost — and culture — of retiring in two of America’s most iconic zip codes.


