Inheriting Money? 7 Ways to Make Sure Your Windfall Doesn't Vanish
Preserving an inheritance isn’t about spending less — it’s about allocating smart.


When a windfall arrives, the mental accounting trap is immediate: Cash feels like "found money" rather than hard-earned principal.
This cognitive shift can give rise to 'sudden wealth syndrome' — a distortion of financial judgment in which a sudden windfall or inheritance creates the illusion of infinite purchasing power.
From a balance sheet perspective, sudden wealth can be destructive not because of emotion, but because it can convert the windfall into permanent fixed liabilities. Many inheritors fall prey to lifestyle creep, high-risk investments and guilt-driven financial requests from friends and relatives.
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues
Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.
To ensure long-term wealth preservation, beneficiaries must shift from an emotional mindset to a professional one.
Here are seven ways to safeguard a windfall and build multigenerational financial security.
1. Enforce a mandatory 'decision freeze'
Before deploying a single dollar, place the capital in high-yield savings accounts, short-term Treasury bills or money market funds. Spread funds across institutions to remain under FDIC insurance thresholds of $250,000 per depositor per bank.
How this protects your money. Temporarily parking your funds creates a crucial "decision-free zone." This cooling-off period halts impulse choices and gives you the time to assemble a team of qualified professionals — such as tax strategists, estate attorneys and financial advisers. Stepping back allows you to build a thoughtful strategy, ensuring your windfall transitions safely into enduring wealth.
2. Divide your windfall into strategic buckets
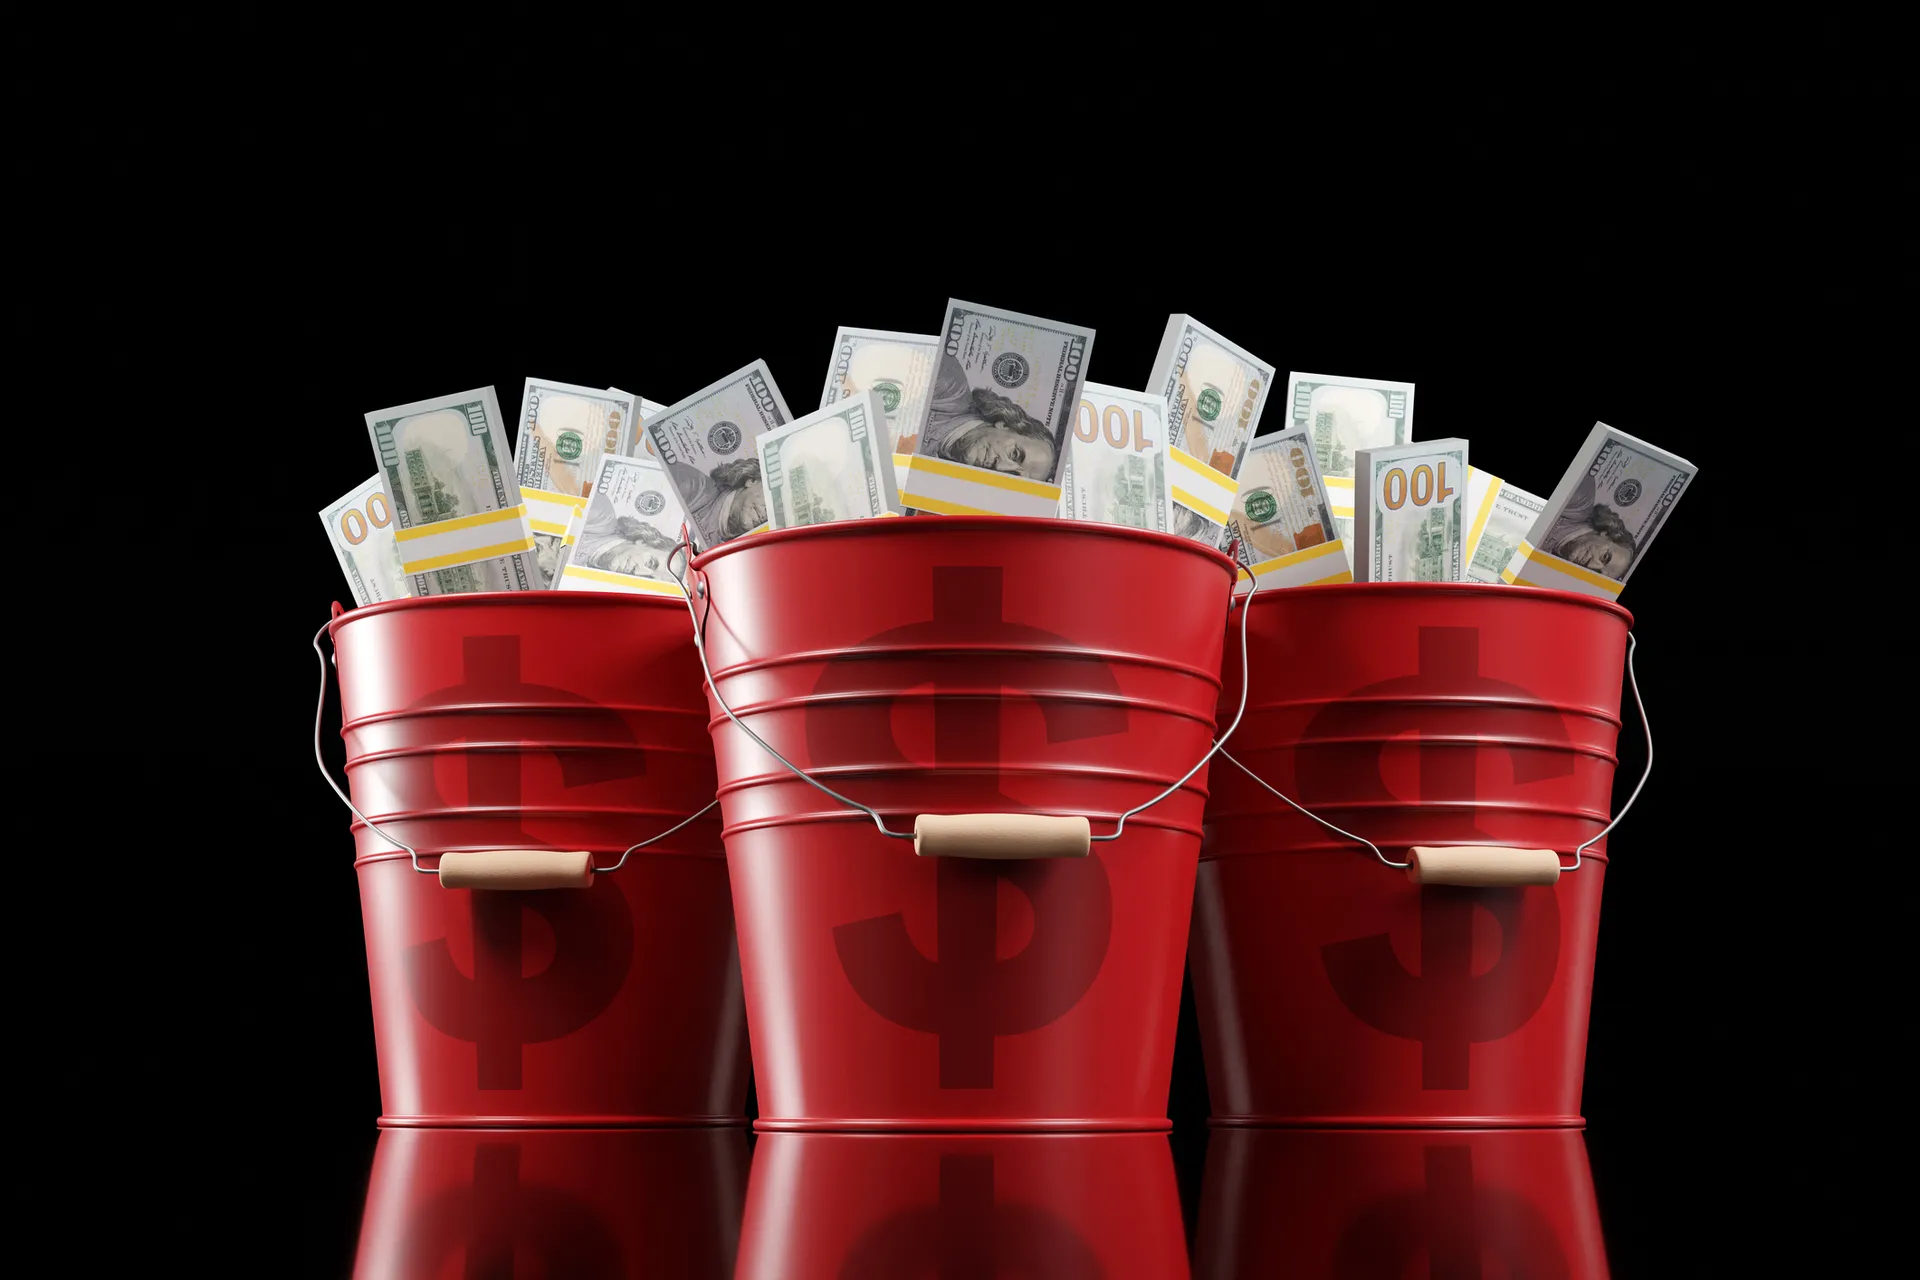
Rather than treating an inheritance as one lump sum, divide the windfall into distinct financial buckets using a disciplined allocation framework. Consult a financial professional to help you decide how much to allocate to each bucket and to refine your investment choices.
- Long-term investment growth. index funds, ETFs and investment-grade bonds
- Financial foundation & debt reduction. create a six-to-12-month emergency fund, maintain a high-yield savings account and eliminate high-interest debt
- Near-term goals & real estate. fund a primary home down payment and/or capital improvements to a new or existing home
- Controlled fun / guilt-free bucket. use for travel, major purchases and family gifts
How this protects your money. Allocating a strict 5% to 10% "fun bucket" creates a psychological circuit breaker. It satisfies immediate lifestyle desires without eroding the 90% core engine required for long-term compounding.
3. Wipe out high-interest liabilities first
Pay off variable credit card debt, personal loans or high-rate auto financing immediately before committing to long-term market investments. Paying off any lingering student loan debt will also save you money on interest.
How this protects your money. Retiring an 18% or 22% interest liability delivers an immediate, risk-free return equivalent to that APR. It permanently reduces monthly baseline overhead and creates greater budget flexibility.
4. Build an objective advisory team
Assemble a fee-only certified financial planner (CFP), a certified public accountant (CPA), and an estate attorney. Avoid commission-based brokers or product sellers pitching complex, illiquid instruments.
How this protects your money:. A CPA ensures compliance with tax rules (such as SECURE Act 10-year distribution rules for inherited IRAs), while a fee-only adviser acts as an objective barrier between the inheritor and impulse decisions.
5. Pass the no to your financial team
Requests for loans, business seed funding or gifts from friends and extended family are a leading driver of rapid wealth depletion. You might feel bad saying no even though it's the best thing to do.
How this protects your money. By shifting distribution authority to a formal policy or advisory team, the inheritor uses a scripted defense: "My estate plan and financial adviser manage all portfolio distributions under a fixed annual schedule, so I cannot write personal checks." This removes personal conflict while preserving relationships.
6. Avoid converting cash into recurring liabilities
A common pitfall is purchasing high-maintenance assets — such as luxury vehicles, second homes or boats — using lump-sum cash.
How this protects your money. A lump-sum inheritance can drain quickly when tied to permanent, recurring liabilities such as property taxes, HOA fees, maintenance and insurance premiums. Covering ongoing fixed costs strictly with earned income safeguards the underlying inheritance.
7. Adopt the 4% rule for perpetual cash flow
To treat the windfall as a true income-generating asset rather than a declining balance, establish a sustainable withdrawal rate, such as the 4.0% rule.
How this protects your money. On a $1 million invested portfolio, the 4% rule would generate $40,000 in annual supplemental income while allowing the underlying principle to compound alongside inflation, ensuring the capital survives indefinitely.
Spending that has financial return
Here are concrete, financially sound ways to allocate an inheritance that transform a one-time cash windfall into long-term financial resilience:
Expense |
How it helps |
Where to invest |
Why it protects capital |
Primary real estate equity (remodel or down payment) |
Deploying capital into a primary residence converts liquid cash into a hard, tangible asset that grows with appreciation while providing a place to live |
Capital improvement / remodeling and down payment or mortgage reduction |
Unlike luxury discretionary spending, real estate capital stays on your personal balance sheet as equity. However, the key is avoiding "mansion creep" — buying a home so large that property taxes, maintenance and insurance drain your remaining liquid reserve |
Skills education and earning power |
One of the highest-return "purchases" an inheritor can make is investing in their own earning potential or that of their immediate family |
Specialized degrees and executive education |
Unlike physical goods that lose value over time, expanding personal skills creates a compounding source of income that outlives the original windfall |
Generational education and health infrastructure |
Investing in your family removes future financial liabilities from your ongoing baseline budget |
529 college savings plans, preventative healthcare and long-term care planning |
Removing future educational or medical liabilities from your annual operating expenses ensures that future earnings can go straight into retirement savings |
Pace yourself
An inheritance is far more than a financial buffer; it's the physical representation of someone else’s life's work, passed forward to create opportunity. Treating a windfall with intention doesn't mean locking every dollar away in a vault and forgoing life's pleasures — it means establishing clear guardrails so your capital works for you, rather than disappearing beneath lifestyle inflation.
By pausing before acting, funding productive assets and protecting your principal with a disciplined financial plan, you can transform a one-time inheritance from short-lived "mad money" into enduring financial freedom and multigenerational security.
Related Content
- Manage an Inheritance Like a Pro in Just 7 Steps
- Could You Handle a Sudden Windfall? Take Our Quiz
- The Inheritance Investment Quiz: Will You Grow or Blow Your Family Legacy?