Dignity, Identity and Vulnerability: How to Protect an Aging Parent's Finances Without Causing Conflict
Dignity, identity and vulnerability may sound like the soft side of planning for an aging parent, but it's an essential framework that can help families avoid conflict, confusion and court.

Every winter, the mail brings a 1099-DIV. It reports dividends and takes about four seconds to understand.
Another "DIV," the one that can shape a family's next decade, never arrives in an envelope. It shows up in a phone call that begins, "Something happened to dad."
That DIV is dignity, identity and vulnerability — an acronym I've developed over decades advising families through some of their most sensitive planning moments. It is a simple framework I regularly use to help families move these conversations from crisis management to thoughtful preparation.
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues

Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.
In fact, I have rarely seen an estate plan fail because the documents were poorly drafted. I have often seen one fail because no one had the hard conversation while mom or dad was still fully in charge.
Documents don't fail families. Timing does.
You can use the same framework to help aging family members preserve their sense of autonomy. I'd urge you to address each part before a crisis forces the conversation.
Dignity
Dignity requires two conversations. The first should happen when parents are around 65 to 70 and should feel like basic housekeeping:
- Who is named under the power of attorney?
- Who is the healthcare agent or successor trustee?
- Are those people still alive, willing and right for the role?
Framed this way, the discussion is routine maintenance, like updating insurance coverage or re-registering a car. Framed as decline, it becomes a referendum on whether dad is slipping.
The second conversation, about a parent actually stepping back, is harder. It should be triggered by observed changes, not a birthday.
Families that had the first conversation early have a framework for the second. Those that skipped it may find themselves improvising in a hospital corridor.
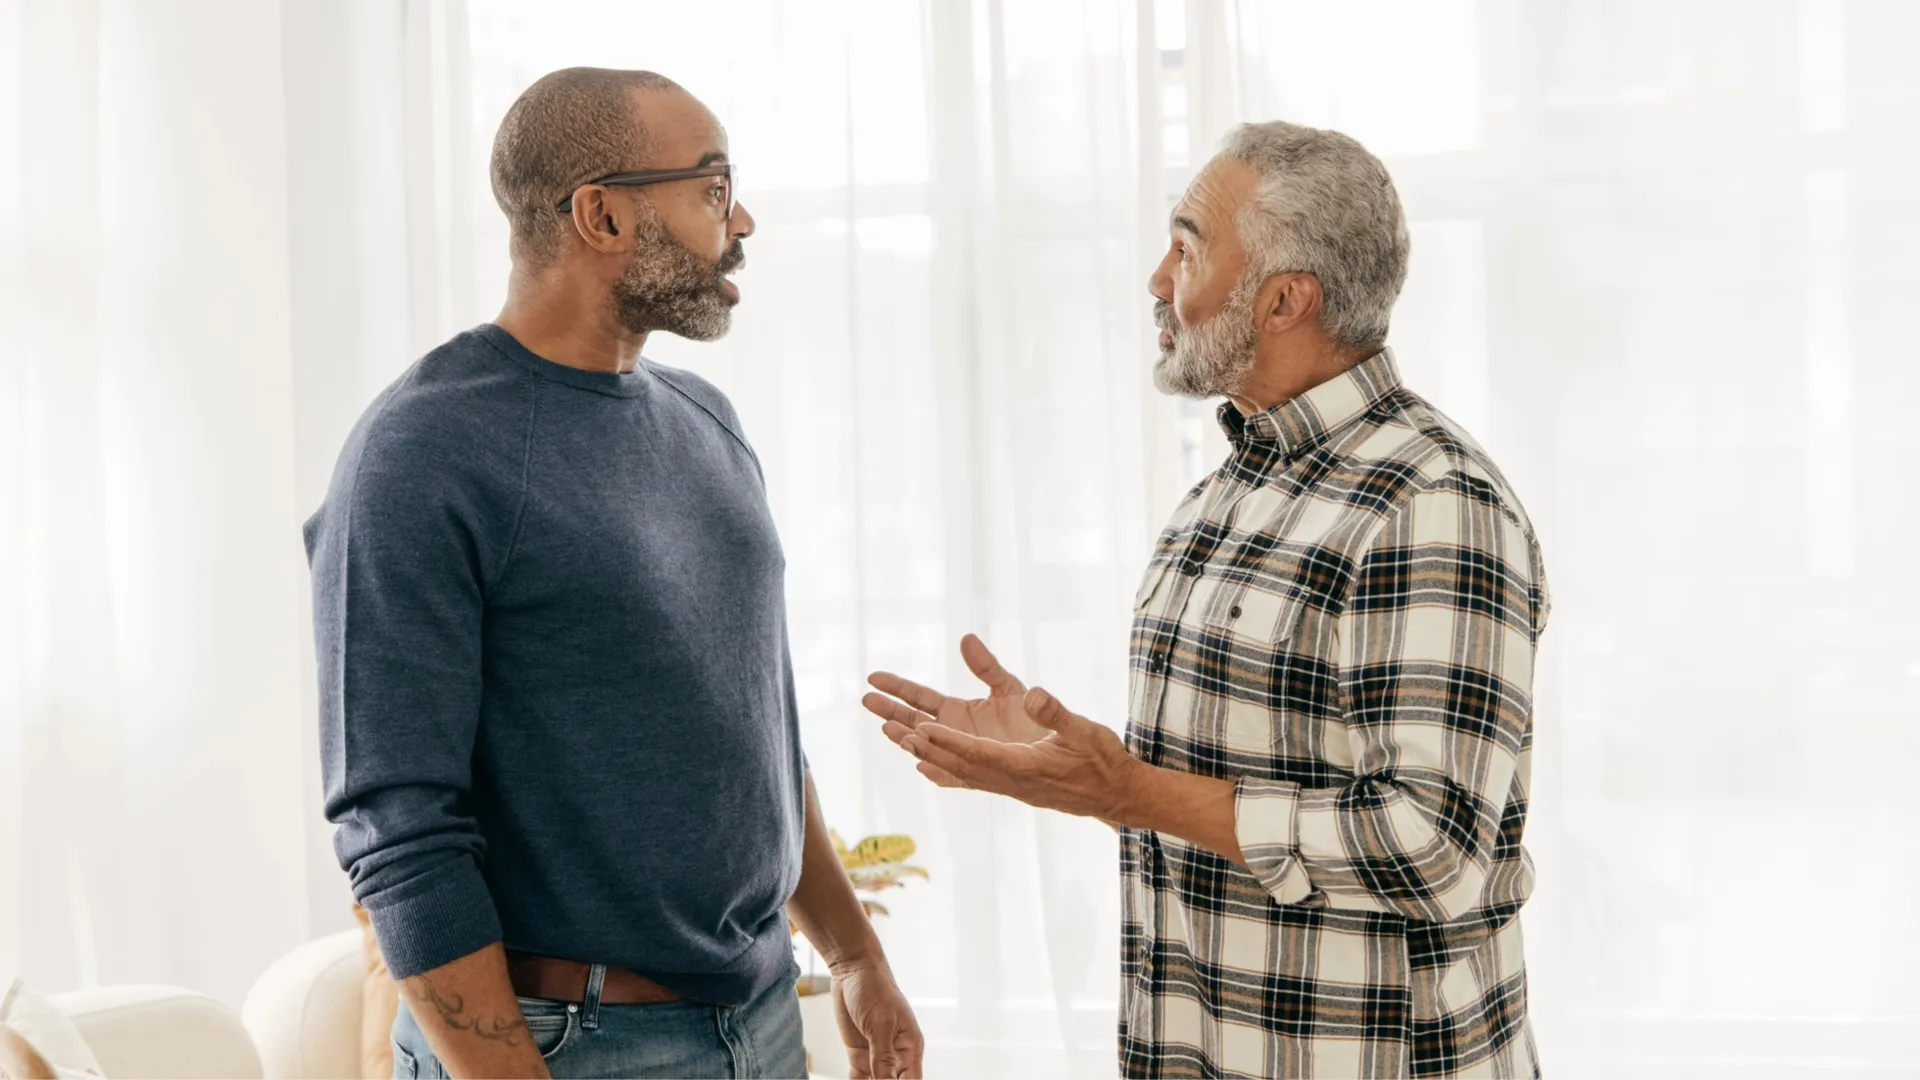
Dignity during the second conversation is largely a matter of specificity. "We noticed the electric bill was paid three times in March" invites a shared solution. "We don't think you can handle this anymore" invites a fight.
Capacity isn't an on-off switch. It's task specific and often diminishes over time. A parent may no longer manage a complex portfolio but remain fully capable of deciding where to live, who visits and what medical care to receive.
A capacity evaluation, framed properly, is not a family giving up on a parent. It protects the parent's stated wishes from later challenge by someone who preferred a different outcome.
The transition does not have to happen all at once. Start with transaction alerts or view-only account access, then move to help with bill paying and transfer formal authority only when the facts require it. The least restrictive assistance protects the parent without ignoring real changes.
One effective approach is a low-key annual roles review. Because it is routine and applies to everyone, an eventual transition can feel more administrative than personal.
But timing is only part of it. For many parents, authority is also part of identity.
Identity
This is the part families forget. To an adult child, serving as trustee may look like paperwork. To the parent who built the business that funded the trust, signature authority may mean relevance.
Ask someone to surrender it, and the conversation is no longer about administration. You're asking that person to accept a smaller version of themselves — and to alter their perceived identity.
I have watched this play out more than once. In one family, for example, a manufacturing founder deflected succession conversations for years. We eventually stopped describing the trustee transition as "stepping down" and began calling it a promotion to chair.
The founder kept an honorary seat at the table, remained involved in the family's philanthropy and relationships, and allowed a successor trustee to handle discretionary distributions.
A respectful new role preserves identity while transferring responsibility. The arrangement must be genuine and carefully structured. A parent who retains too much control over transferred assets may create unintended tax consequences. Give your parent a title, a seat and a voice, but ask your estate attorney to define which powers stay and which go.
Even when the parent accepts a transition, the harder conflict may be among the adult children. Siblings often disagree about whether mom "still has it," with each hearing something different in the same phone call.
That is why vulnerability planning must protect the parent from outsiders and protect the family from avoidable uncertainty.
Vulnerability
Vulnerability runs in two directions. One comes from people who may take advantage of the parent. The other comes from documents so vague or rigid that the family cannot act when necessary.
Financial exploitation is the risk most families expect. It is usually closer to home than they think. The person exploiting a parent is more often someone with a key to the house than a stranger overseas.
You can improve oversight without transferring control:
- Name a trusted contact at each financial institution
- Grant a trusted second person view-only access to accounts
- Turn on transaction alerts and set them low enough to be useful
- Consider requiring a second signature above an agreed dollar amount
- Consolidate stray accounts so there is less to monitor
The legal exposure is the one families tend to discover too late. A well-drafted trust or power of attorney should contain clear, objective triggers for when a successor trustee may act.
Here's an example of why that matters. One matriarch's trust required two independent physicians to certify her incapacity before a successor trustee could take over. When her children disagreed sharply about her condition, the document made the call. No one filed for guardianship, and the siblings still speak.
Another document, drafted with more precision, required certification by a physician "board-certified in the illness causing the incapacity." The parent was later diagnosed with Alzheimer's disease, but physicians are not board-certified in Alzheimer's itself. They may be certified in neurology, geriatric medicine or psychiatry. The clause was well-intentioned but impossible to satisfy. Ultimately, the family needed a court proceeding to answer the question the document was supposed to resolve.
Functional standards travel better than clever ones. Rather than anticipating every diagnosis, a document might call for a physician with relevant expertise to evaluate the incapacity involved.
What families can do now
Read the incapacity clause in your parent's trust or power of attorney out loud.
Can you identify who makes the decision, what standard applies and how the determination must be documented? If not, the clause deserves another look.
Then take four practical steps:
1. Confirm that the named agents and successors remain appropriate
2. Add trusted contacts to financial accounts
3. Put an annual roles review on the family calendar
4. Ask not only what a parent may need to give up, but what the parent wants to keep
Technical documents matter. But in families, human issues often decide whether those documents work quietly or end up before a judge.
The best feature of this DIV is that it is declared, not received. A family gets to choose when the conversation begins.
Handled early, it may cost an awkward afternoon. Handled late, it can cost much more.
The author takes sole responsibility for the views expressed herein, and these views do not necessarily reflect the views of the author's employer or any other organization, group, or individual.
Related Content
- The Holidays Are a Time for Sharing (Your Wishes)
- Caring for Aging Parents: An Expert Guide to Easing the Financial and Emotional Strain
- How to Plan Ahead After a Loved One's Dementia Diagnosis
- A Rare Moment in Family Tax Planning Has Arrived: 3 Ways to Seize It
- Smiley Faces in Serious Places: Emoji Use Pops Up in Legal Battles Over Inheritances