Protect Your Family's Future: Avoid These 12 Common Estate Planning Mistakes
Don’t make these common estate planning mistakes and your loved ones will thank you.


Estate planning mistakes can derail the best-laid plans to protect your family's financial future — from having no plan at all to outdated or missing documents, to choosing the wrong executors.
Learning the basics of estate planning benefits everyone. It's about empowering the people you trust the most to handle your medical, financial, and legal affairs if or when you can't.
Having a comprehensive estate plan will also spare your heirs the pain and expense of determining how to allocate your money and property while they’re sad and grieving.
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues
Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.
What is an estate plan?

An estate plan includes several legal documents that outline what happens to your assets and liabilities when you die or become incapacitated. At a minimum, it includes a last will and testament, a living trust, an advance directive, and a power of attorney.
Estate planning isn't just about wealth — it ensures your medical preferences are honored and reduces family conflicts. Crucially, creating a plan while you're healthy means you will maintain control over these vital decisions.
Planning while of sound mind ensures that you, not a court, decide how your assets are handled and prevents your estate from defaulting to the state. That is why an estate plan is critical for everyone, whether you're a millionaire or just starting out.
Common estate planning mistakes to avoid
Creating an estate plan can be complex and emotionally challenging, which might explain why more than half, or 56%, of U.S. adults have no estate planning documents — no will, trust, Medical POA, Financial POA, or HIPAA authorization — essentially unchanged from 55% in 2025, according to the Trust and Will 2026 Estate Planning Report.
What's even more concerning is that around 27% have never discussed end-of-life wishes with loved ones and do not plan to, and 42% of those surveyed would not know what to do if a family member died today.
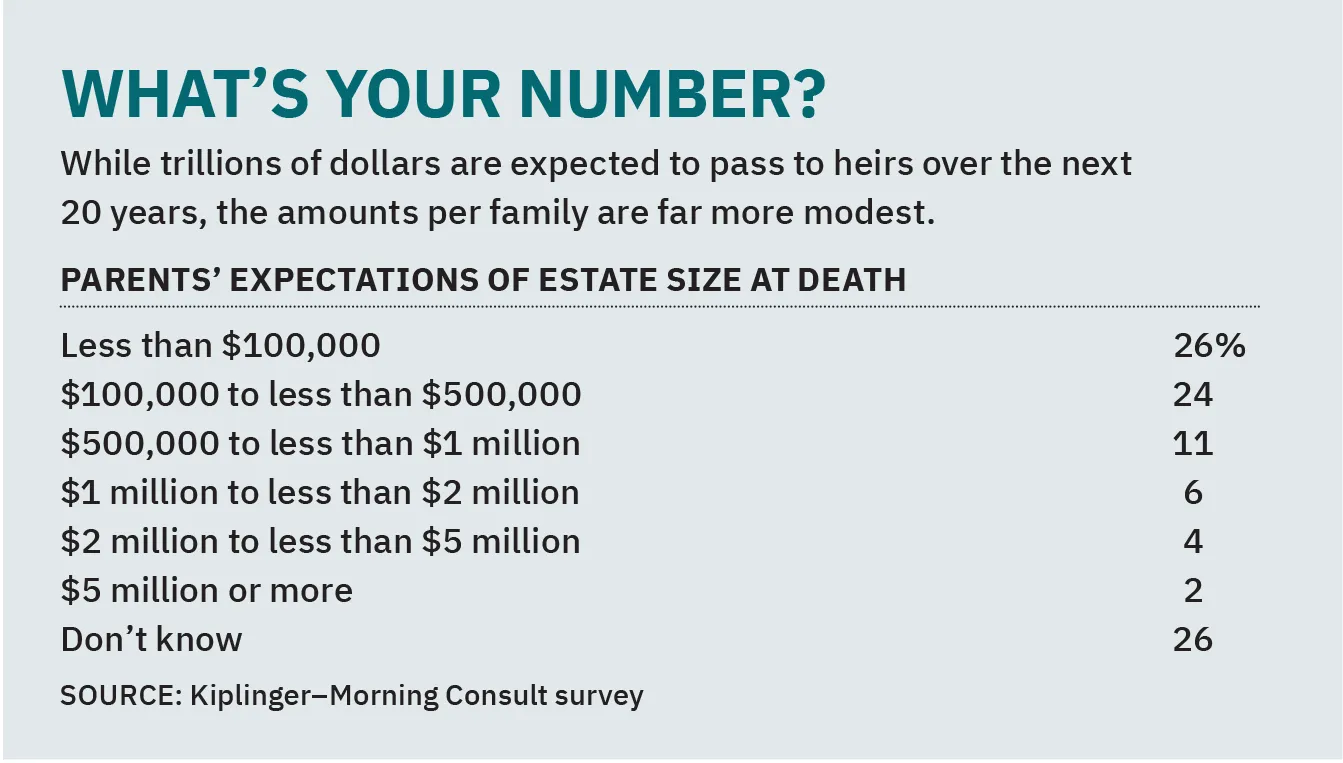
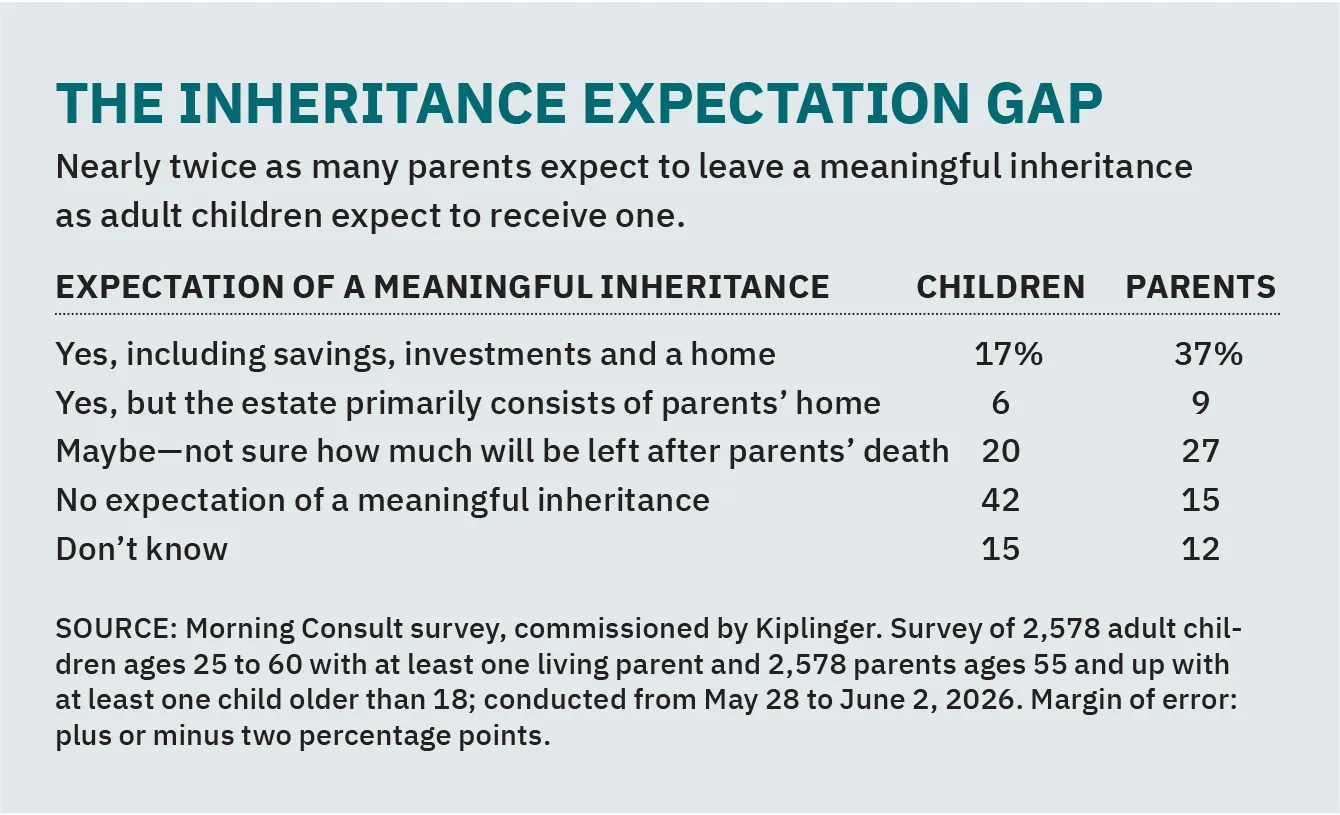
A recent survey from Kiplinger-Morning Consult showed that approximately two in five families have never discussed inheritance plans.
However, you can never make an estate plan too soon, because you never know when it will be too late. To avoid trouble down the road, steer clear of these 12 common estate planning mistakes.
1. Procrastinating
You don’t want to be without an estate plan if you become incapacitated because of a health emergency, such as a stroke or heart attack. Yet according to a 2026 survey by Trust & Will, only 26% of adults have a will (down from 31% in 2025 ). Among people who already have one, 14% cited a health scare as the reason they created one.
This wait-and-see strategy raises two serious problems:
First, your loved ones might face lengthy legal proceedings to access your estate if you die without a will.
Second, without an advance directive, a section of an estate plan that dictates your medical preferences if you're incapacitated, your family won't know what kind of care you prefer.
2. Creating an estate plan on your own

Estate-planning documents that are incomplete or contain errors can cause complications when you pass. Consider hiring an estate attorney who understands the legalese to help you craft a comprehensive estate plan.
Generally, estate lawyers charge from $150 to $350 per hour for an estate plan, depending on the complexity of the client’s estate and often their location, according to Greiner Law Corp.
However, many estate attorneys offer free initial consultations or charge a flat fee for writing a will. Fortunately, there are ways to save money on an estate plan.
Read: How to Save Money on Estate Planning to find out how.
You can find an estate attorney in your area using an online directory such as Justia, Legal Match or the American College of Trust and Estate Counsel (ACTEC).
3. Leaving loved ones uninformed
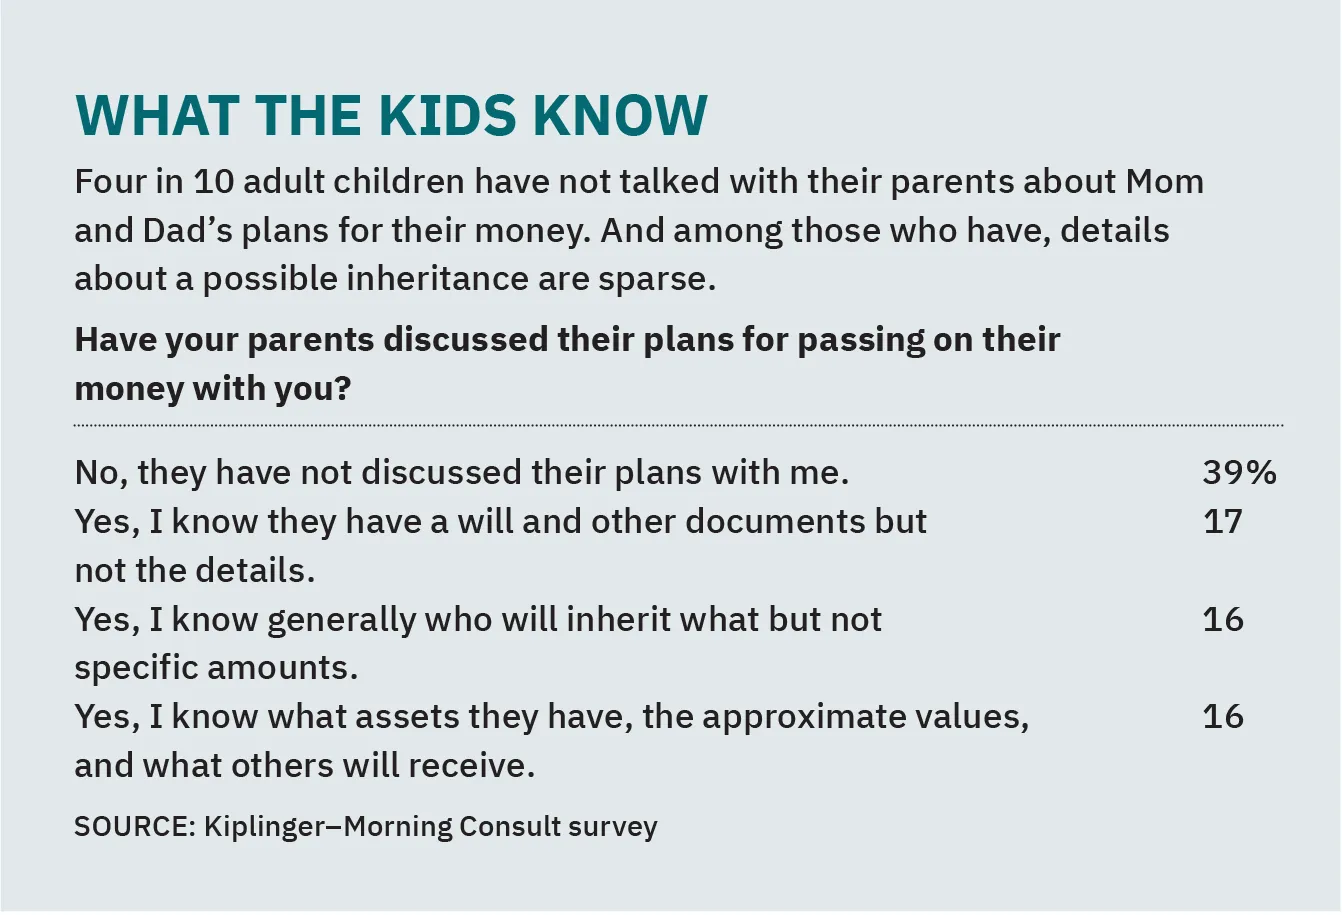
Sharing your estate plan with your family and heirs can help prevent confusion, conflict and unnecessary stress. Although the conversation can be difficult as you face your own mortality, it's important to sit down with the people who matter most to you in your life and have an open conversation about your intentions while you still can.
4. Keeping documents locked up

Estate documents kept in a safe deposit box or a safe inside your home might be difficult to access. Instead, provide copies of your estate plan to your appointed executor or trustee, a trusted family member and your estate lawyer. Make sure all family members have contact information for each of these people.
However, if you do choose to leave the documents in a safe, fireproof and waterproof place, make sure your heirs or executor have the combination or key.
5. Missing key documents
An incomplete estate plan can create a heap of problems — and the potential for disputes among heirs when you pass. Make sure your plan includes these essential documents:
- Last will and testament. Often referred to as a "will," a last will and testament outlines your final wishes and instructions for the distribution of your assets and the management of your affairs after you pass.
- Beneficiary designations. Make sure to assign beneficiaries for bank accounts, 401(k) and IRA accounts, pensions and life insurance policies.
- Durable power of attorney for medical care. This appoints a person to make medical decisions for you if you should become mentally or physically incapable of making them yourself. It often includes an advance health care directive, which instructs your family and doctors on whether to use life support.
- Durable financial power of attorney. This assigns an individual to manage your assets if you become incapacitated.
- Funeral instructions. Specify whether you’d like a burial or a cremation and the type of funeral service you want.
- Proof of identity. Gather your Social Security card, birth certificate, marriage and/or divorce certificate and any prenuptial agreements.
- Deeds or loans for large assets. Collect this paperwork for homes, boats and other big assets.
- A living trust or a revocable trust. A living trust is not required for estate planning, but it can help your heirs with a smoother transfer of assets after you die.
6. Overlooking digital assets

Many people forget to account for their digital assets, such as cryptocurrencies, social media accounts, cloud storage and digital files, when creating an estate plan. Consider assigning a digital fiduciary in your estate plan who has the right to access your digital assets after you pass.
7. Forgetting about final arrangements
No one eagerly dives into planning their own funeral or final arrangements. If you're young, you think you'll live forever; if you're older, the inevitable feels too close for comfort.
Making final arrangements, setting aside money for a funeral, choosing a burial plot, picking out songs and deciding on a coffin or other vessel makes it easier for those you leave behind.
Besides, funerals can be expensive. The average funeral cost held steady for some time around $8,300, although costs have risen slightly recently due to inflation. Costs include a burial service and viewing, depending on where you live. Add in a vault, and you'll pay over $10,000. The median cremation cost is still $6,300, according to the National Funeral Directors Association.
8. Forgetting about taxes
Estate tax liability can put a dent in any plan. But unless your estate is very large — $15,000,000 in 2026 (up from $13,990,000 in 2025) — you might not have to worry because your estate won't be taxed at the federal level. Keep in mind, thanks to recent legislation (the One Big Beautiful Bill Act), the exemption has been permanently increased and indexed for inflation—no reversion to the former $5 million limit is expected.
In addition, your state might or might not have a state estate tax, so check this out before you write up your will or trust. More than 30 states have no death taxes and six states have significant death taxes.
9. Not updating your plan

Don't worry about updating your estate plan every month or even every year. However, reviewing and revising your estate plan after major life events — a marriage, divorce, birth of children or grandchildren, or the acquisition of new assets — can prevent unwanted consequences, such as your assets passing to unintended beneficiaries.
Because your assets might change, as well as your personal options, beliefs and relationships, it’s still a good idea to go through your estate plan about every three to five years.
10. Appointing the wrong executor or trustee
No matter how much time and effort you put into planning your estate, your wishes might backfire if the wrong executor is chosen. Choosing someone who might have a conflict of interest can lead to problems when it comes time for them to administer your estate wishes. Select an individual (or individuals) who are unbiased, and get their permission before you assign them as an executor or trustee.
11. Being unaware of how recent legislation has changed estate planning

The "One Big Beautiful Bill," signed into law by President Trump in July 2025, extended and expanded key provisions from the 2017 Tax Cuts and Jobs Act (TCJA). The Bill raised the federal estate, gift, and generation-skipping transfer (GST) tax exemption to $15 million per individual and to $30 million for married couples starting January 1, 2026, with inflation adjustments thereafter.
In 2027, the federal estate, gift and generation-skipping transfer tax exemption is projected to jump to $15,340,000 ($30,680,000 for married couples), according to USTaxTools.
This protects more of what you leave to heirs from estate taxes and provides long-term stability for transferring wealth across generations. It also reduces the need to gift large portions of your estate before year-end deadlines. The legislation also updates tax-advantaged tools, establishing permanently higher contribution limits and expanded qualified withdrawals for ABLE accounts and 529 plans.
12. Underestimating the consequences of not having an estate plan

The consequences of not having an estate plan can lead to needless complications for your loved ones after your passing. Without a clear plan in place, state laws will decide how your assets are distributed — not you. Those decisions may not align with your wishes, resulting in delays in the distribution of your assets and potentially costly legal battles. Your loved ones may find themselves in probate, which can be time-consuming and emotionally draining, especially during an already difficult time.
Without an estate plan, your family won't know your medical or financial wishes. Lacking a power of attorney or healthcare proxy can trigger confusion, disputes, and stress during a crisis. Creating a plan early prevents this hardship, ensuring your wishes are honored and your loved ones are protected.
Related Content
- 7 Estate Planning Best Practices
- Key Components of an Estate Plan — and 7 Others to Consider
- Estate Planning: Who Needs a Trust and Who Doesn't?
- Estate Planning Checklist: 13 Smart Moves
