Inflation Is at 3.70%: These Savings Accounts Are Outpacing It
Inflation is running above the Federal Reserve's target, but some savings accounts and CDs still offer rates that can help your cash keep pace.


The Bureau of Labor Statistics released its September Consumer Price Index (CPI) report. In September, the CPI rose 0.6%, seasonally adjusted (SA) from August, and 3.7% over the year, not seasonally adjusted (NSA).
The escalating war in Iran has spiked gas prices to the point that higher inflation persists. David Payne of the Kiplinger Letter notes headline inflation will likely be around 4.0% to end the year, without a resolution.
It isn't all doom and gloom for savers, though. I'll show you where to earn the most based on your savings goals, what the inflation number means for Federal Reserve policy and other steps you should consider.
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues

Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.
These are the savings accounts outpacing inflation
If you are looking to build an emergency fund or have a short-term savings goal where you need cash access, I would consider a high-yield savings account, but look carefully at the rates, as many don't outpace current inflation.
Newtek Bank offers a savings account earning 4.20% APY with no monthly fees. This will keep you ahead of inflation in the interim.
The benefit is that you can build your savings without tying your money up as you would with a CD. Plus, if price pressures continue to build, the Federal Reserve could raise interest rates, which could also push rates on high-yield savings accounts higher.
Will this inflation news change Fed policy?
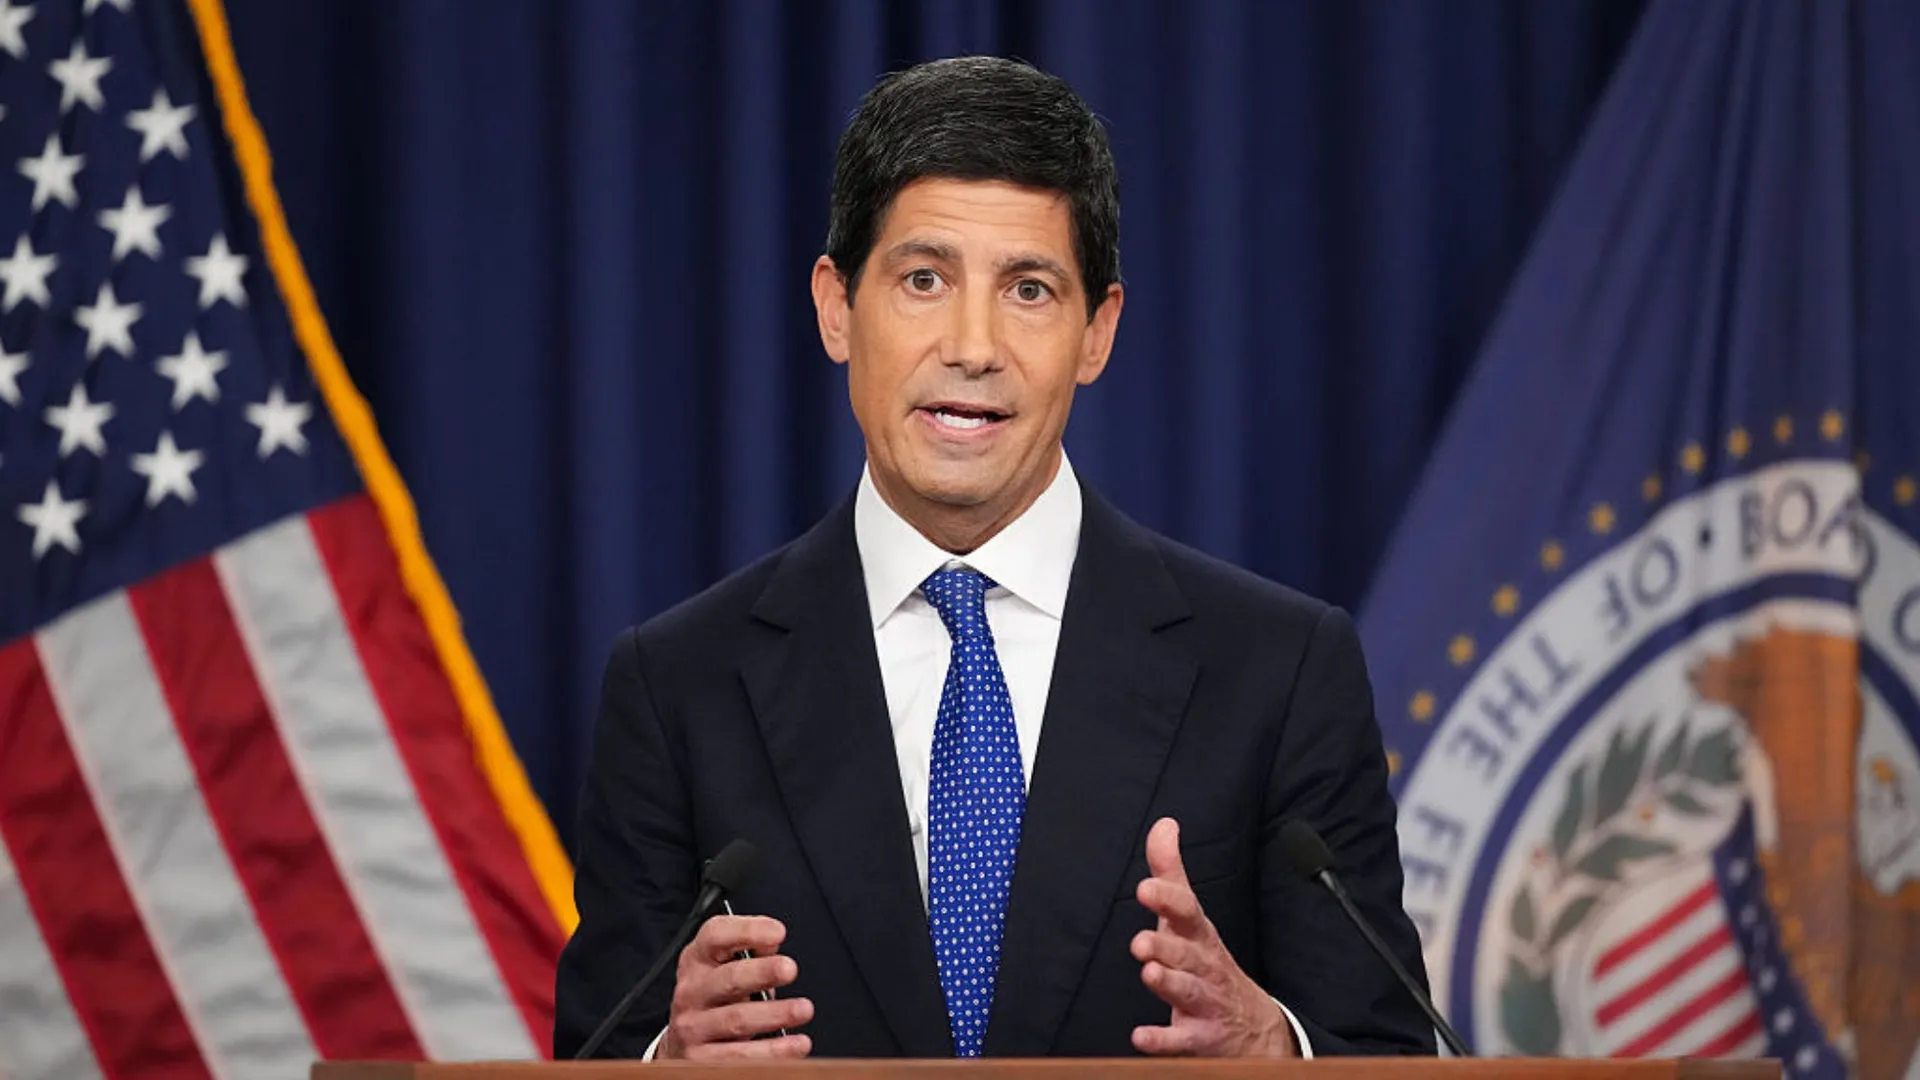
The Fed meets on October 27 and 28, with CME Group FedWatch projecting a 56% chance the Fed will keep rates unchanged after a rate hike at its September meeting. However, that might not be the only rate hike we see this year.
Boston Federal Reserve President Susan Collins said she believes the Federal Reserve will need to raise rates again before the end of the year to slow inflation, according to Reuters.
And higher prices are the trend we could see play out. "Full normalization of energy costs could take well into 2027 because of extensive damage to energy infrastructure in the Middle East," writes Payne, staff economist and reporter for The Kiplinger Letter, in the Kiplinger inflation outlook.
"Eventually, food prices will start rising, as one-third of the world’s fertilizer supply is produced in the Persian Gulf region."
Are CDs a smart move right now?

Yes, they can be. I like short-term CDs right now because they can help you earn a rate higher than inflation. Plus, you can pivot to other investments when the CD matures if economic conditions change.
If inflation continues to rise, the Federal Reserve could respond by raising interest rates again to help cool price pressures. That could push yields on CDs and other savings products higher. With a short-term CD, you won't have your money locked up for long, potentially giving you an opportunity to take advantage of higher rates when your CD matures.
However, a long-term CD can work, too, if you're looking for a less risky place to keep some of your cash as you approach retirement. CDs offer a fixed return, so your rate won't change during the term once you open one.
Here are some of the best CD rates I found:
Account |
APY |
Min Deposit |
Term |
4.00% |
$1,000 |
3 months |
|
4.25% |
$5 |
6 months |
|
4.30% |
$1,000 |
1 year |
|
4.40% |
$2,500 |
2 years |
|
4.45% |
$500 |
3 years |
|
4.45% |
$500 |
4 years |
|
4.60% |
$1,500 |
5 years |
|
4.60% |
$100,000 |
18-month jumbo CD |
What should you do amid rising inflation?
First, make sure you have an emergency savings fund with at least six months of expenses in a high-yield savings account. I suggest using Newtek Bank since it outpaces inflation.
Once you've built your emergency savings, consider whether some of the money you won't need in the near term could be invested for longer-term goals. Stocks have historically offered the potential for returns that outpace inflation over the long run, though they also come with the risk of losses.
Where you put that money will depend on your goals, timeline and tolerance for risk. Kiplinger Personal Finance Magazine recently looked at where to find top yields for the rest of 2026. You can also explore our picks for the best Vanguard ETFs and highest-yielding dividend stocks in the S&P 500.
And if you need help with where to invest your money, use the Bankrate tool below to find a reputable adviser to assist you, as they can create a plan based on your finances, goals and risk tolerance:
Related content