The Benefits of a Special Needs Trust
This estate-planning tool provides financial security for a loved one who has a disability.
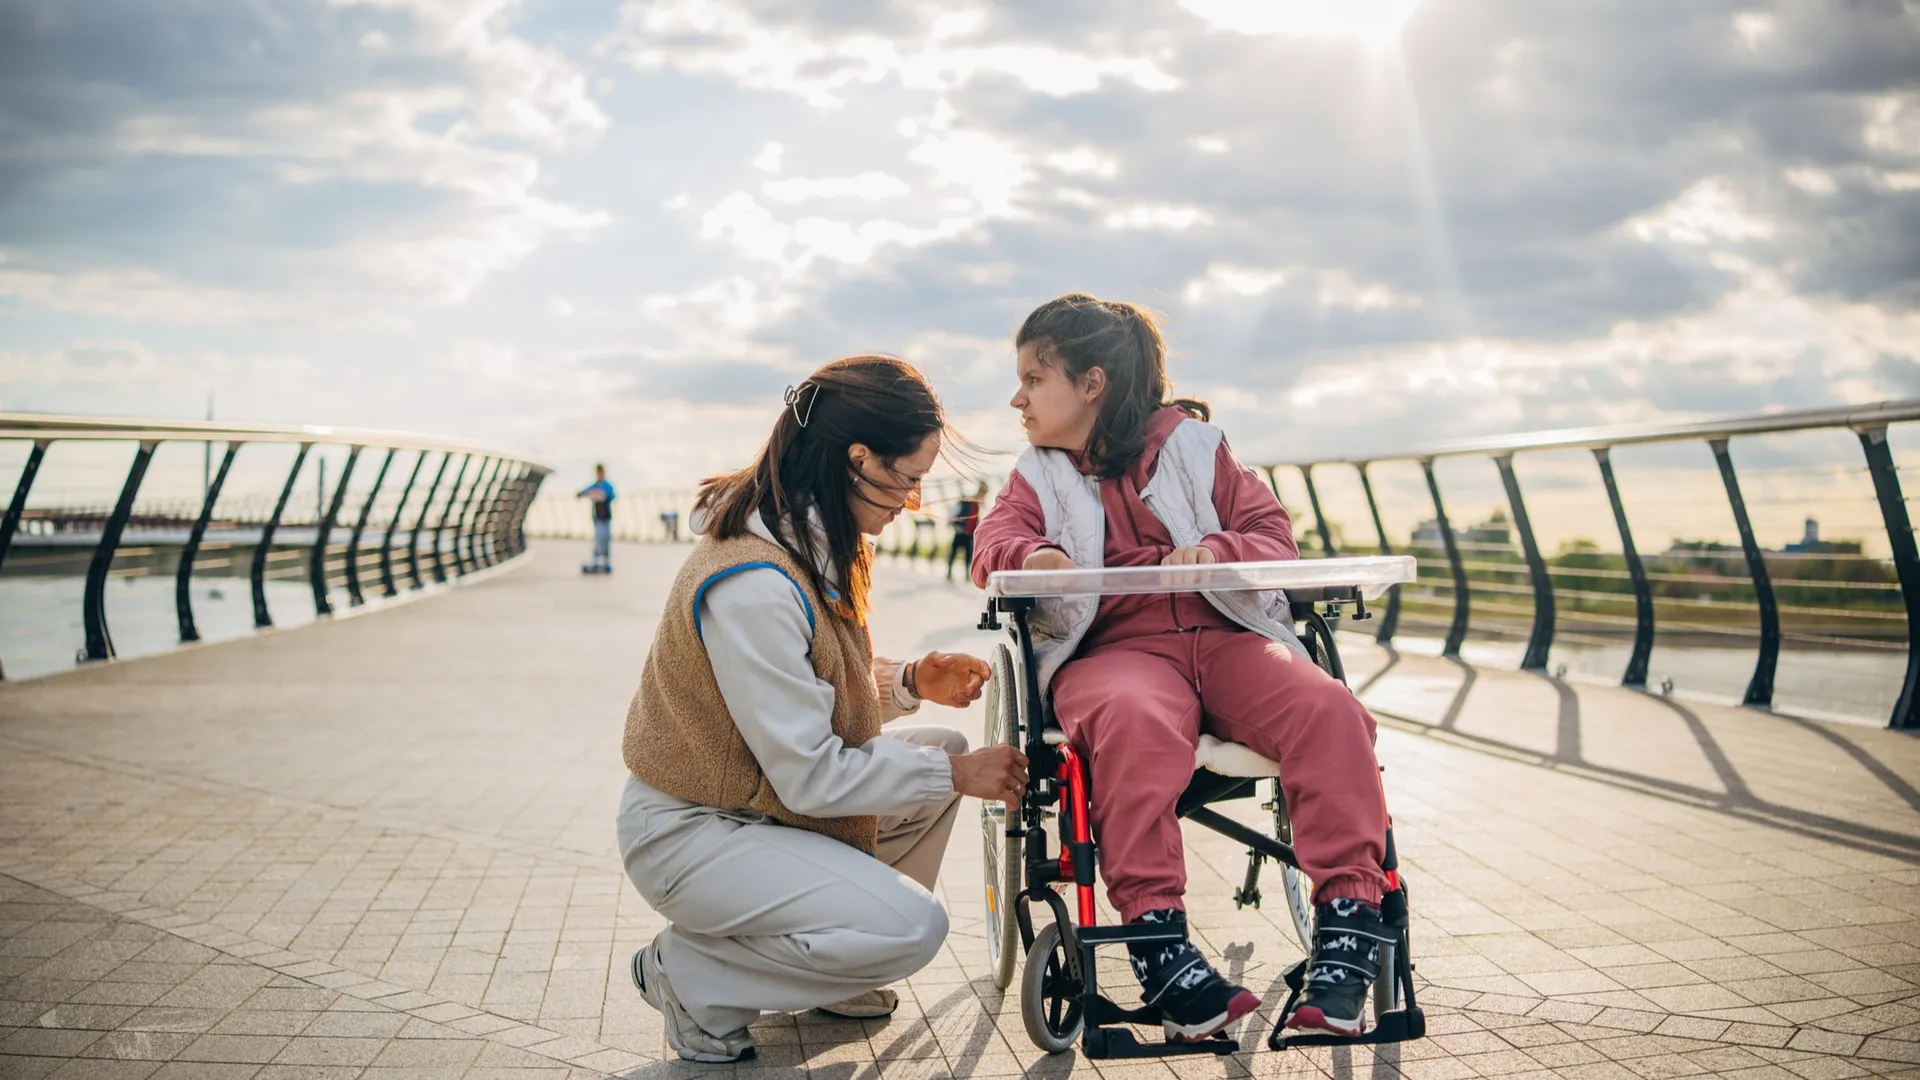
If you take care of a child or another loved one who has a disability, you'll need a plan to provide for them after you pass away. One option is a special needs trust, a legal entity that holds assets for the beneficiary's future care without affecting their eligibility for income-based government services, such as Medicaid health insurance and Social Security Supplemental Security Income. A special needs trust adds another layer of financial support for your loved one and reduces their vulnerability to exploitation.
These trusts are commonly created for people who have permanent or severe disabilities that prevent them from working, such as vision loss, paraplegia or chronic mental illness.
A special needs trust funded by someone other than the beneficiary is known as a third-party trust. By contrast, a first-party trust is funded with the disabled person's assets.
From just $107.88 $24.99 for Kiplinger Personal Finance
Become a smarter, better informed investor. Subscribe from just $107.88 $24.99, plus get up to 4 Special Issues

Sign up for Kiplinger’s Free Newsletters
Profit and prosper with the best of expert advice on investing, taxes, retirement, personal finance and more - straight to your e-mail.
Profit and prosper with the best of expert advice - straight to your e-mail.
A benefit of a third-party trust is that it offers more agency in how the remaining assets are distributed after the beneficiary dies, says Nicky Amore, a certified financial planner and chartered special needs consultant at Parallel Advisors in San Francisco. The money may, for ex-ample, go to a sibling or a favorite charity. With a first-party trust, however, any remaining funds must first be used to reimburse Medicaid for services the beneficiary received during their lifetime.
A third-party trust can be revocable, meaning that you can change the terms after it's established, or irrevocable, meaning that it can't be easily altered or terminated. Families often choose to set up an irrevocable trust to provide the strongest long-term protection.
Funding the trust
You can put a variety of assets in a special needs trust, including cash, real estate, and investments such as stocks or bonds.
If you have a life insurance policy, you can list the trust as the beneficiary, says Jehan Crump-Gibson, founder and managing partner of Great Lakes Legal Group in Southfield, Michigan. If you do this instead of designating the disabled individual as the beneficiary, the proceeds won't count as income that could jeopardize their government benefits. Similarly, you could name the trust as the beneficiary on your retirement accounts, such as 401(k)s or IRAs.
The beneficiary can use funds from the trust to help pay for expenses that government benefits or other income don't cover, such as caregiving services, medical equipment and supplies, transportation, and travel and entertainment.
Designating trustees
A trustee manages the assets in the best interest of the beneficiary. While living, the parents (or other individual who established the trust) may choose to act as trustees.
But you'll need to name a successor trustee to take on the responsibility after your death. Amore advises using a corporate trustee, such as a bank, to be an impartial guardian that can take care of such tasks as record-keeping and paying taxes. A corporate trustee may charge 1% to 2% of the trust's assets each year in fees. You could also designate a trusted friend or family member as a co-trustee.
Amore recommends giving trustees a letter of intent that details your loved one's medical and emotional needs. While the document isn't legally binding, it can provide valuable direction on the beneficiary's abilities and interests and outline your preferences for care.
Note: This item first appeared in Kiplinger Personal Finance Magazine, a monthly, trustworthy source of advice and guidance. Subscribe to help you make more money and keep more of the money you make here.
Related Content
- You've Got a Trust: Now Who Should Be the Successor Trustee?
- The 5 Essential Trusts You Need for 2026 Estate Planning
- Revocable vs Irrevocable Trusts: It Comes Down to Control vs Protection