
For a long time, "unlimited" phone plans felt like the safe choice. You paid one flat monthly bill and didn't have to think much about how many texts you sent or how often you opened an app on the go. But for many people, that peace of mind now comes with a higher price tag, especially when most of the day is spent connected to Wi-Fi at home, work or around town.
That's why some light phone users are starting to look at pay-as-you-go plans again. Instead of paying $70 to $100+ every month for data you rarely touch, these plans let you buy only what you use and stretch it over time.
For the right kind of user, that shift can mean more control, fewer surprises and a noticeably lower phone bill. The key is knowing when pay-as-you-go actually beats a low-cost monthly plan, and when it doesn't.
What "low usage" really looks like these days

Being a "light user" doesn't mean what it used to. Most people now have unlimited talk and text baked into even the cheapest plans, so the real question is how much mobile data you actually use when you’re away from Wi-Fi.
If you spend most of your time at home, at work or in places with reliable internet, your phone may only dip into mobile data for quick searches, directions or the occasional message with photos. Retirees, remote workers and people who keep a phone mainly for emergencies often fall into this category. Many of them use less than a gigabyte or two of data in an average month.
Taking a look at your phone's data history can be eye-opening. If your "unlimited" plan shows you're barely scratching the surface of what you're paying for, that's usually a sign it's time to consider something simpler.
How pay-as-you-go plans work and who they tend to fit best
Pay-as-you-go plans are built around the idea of buying service in advance instead of paying for it every month. You load your account with a set amount of minutes, texts or data, and you use it at your own pace.
Some carriers let your balance roll over as long as you keep the line active, which means light users can stretch a single refill over several months. That can make these plans especially appealing for people who don't use their phones every day, keep a second line for emergencies or just like the idea of not having another recurring bill to manage.
The trade-off is that you have to stay a little more involved. You'll need to keep an eye on your balance and remember when credits expire. For people who enjoy set-it-and-forget-it billing, that extra step can feel like a hassle. For others, it's a small price to pay for more control over how much they spend.
When a low-cost monthly plan might make more sense
If you use your phone a little bit every day, a basic monthly plan can end up being the easier and sometimes cheaper option. These plans usually include unlimited talk and text along with a small bucket of data, often in the 1-to-5 gigabyte range.
What you get in return is predictability. You know exactly what your bill will be each month, and you don’t have to worry about losing service because a balance ran out or a refill window closed.
Some carriers lower costs even further if you're willing to pay for several months at a time, while others let you fine-tune your plan based on how much data you really need. For steady, moderate users, that combination of flexibility and simplicity can be hard to beat.
Why data, not calls or texts drives your phone bill
Not long ago, phone plans were priced around how many minutes you talked and how many texts you sent. Today, those features are mostly unlimited and barely factor into the cost.
Data is where the money goes. The more you're allowed to use each month, the higher the price climbs. That's also why so many people end up overpaying because it’s easy to sign up for a big data plan "just in case" and then never come close to using it.
If you want to cut your bill, the fastest way is usually to match your plan to your real data habits instead of your worst-case scenario.
How simple carriers compare on price and flexibility
Budget carriers tend to take different approaches, which is why shopping around can make a big difference.
Some, like Tracfone, focus on pay-as-you-go models that reward light, infrequent use with long expiration periods and rollover balances. These work well for people who might go days without touching their phones.
Others, like Mint Mobile, keep prices low by asking customers to pay for multiple months upfront. The longer you commit, the lower your effective monthly cost can be.
Some carriers allow you to customize your plan by selecting exactly how much data you need, helping prevent overpaying. Others, such as Consumer Cellular, focus on simplicity and customer service, typically at a modest premium, appealing to users who prioritize easy support over the lowest possible price.
Hidden costs to watch before switching plans
Before you switch, it's worth looking past the advertised price. Some plans charge activation fees or require you to buy a new SIM card. Taxes and local fees can also nudge the monthly total higher than expected.
Phone compatibility matters, too. Not every device works on every network, and some budget carriers favor newer models. Network priority can also affect your experience since during busy times lower-cost plans may see slower speeds.
For pay-as-you-go users, expiration rules are especially important. Missing a refill deadline can sometimes mean losing any unused balance, which can quickly erase the savings you were aiming for.
How to estimate which plan will cost you less over a year

Instead of focusing on what a plan costs each month, try zooming out to the full year. Look at your past data use and estimate how much you’re likely to need over 12 months.
Then do the math. Add up what you'd spend on refills under a pay-as-you-go plan versus what you'd pay for a basic monthly plan over the same period.
Imagine a basic monthly plan that costs $35 per month for a small data bucket. Over a year, that comes to $420, before taxes and fees.
On the pay-as-you-go side, suppose you buy a $50 refill card that lasts you about four months based on how little data and calling you use. If you only need three refills over the year, your total is $150.
In this scenario, the pay-as-you-go plan saves you $270 for the year, and you're only paying for service you actually use. If your usage stays low, those savings can add up over time, especially if you're managing multiple lines or keeping a phone mainly for occasional calls and emergencies.
Seeing the annual total side by side often makes the better choice obvious especially when you factor in things like unused balances, bulk-payment discounts or surprise fees.
Who should probably skip pay-as-you-go
Pay-as-you-go plans aren't a great fit for everyone. If you use a lot of data, stream on the go or rely on your phone for navigation and travel, you’ll likely burn through refills quickly.
People who use their phones as mobile hotspots or travel internationally may also find these plans too limiting. Running out of data or service at the wrong moment can be more than inconvenient and it can become a real headache.
In those cases, a simple monthly plan with a modest data allowance often offers better value and a lot more peace of mind.
For light phone users though, the goal isn't just to find the cheapest plan on paper. It's to find one that fits how you actually use your phone. Whether that means the flexibility of pay-as-you-go or the ease of a low-cost monthly plan, a quick look at your habits and a little back-of-the-envelope math can turn into meaningful savings over the course of a year.
Related Content:
-
 Nasdaq Hits New Highs on AI Boom Optimism: Stock Market Today
It's a relatively quiet week for earnings and economic data, as markets focus on major themes such as AI and interest rates.
-
 Who Qualifies for the New $90 Medicare Part B Rebate?
Are you getting $90 back on your Part B premiums? Here is a complete breakdown of who qualifies, who is excluded, and when payments arrive.
-
 IPO Strategy: Why Waiting to Invest Pays Off
IPOs are exciting — that doesn't mean they're bargains, and you're usually better off tuning out the hype. Here's a checklist to help you decide when to invest.


-
 How to Give Money to Your Kids Without Setting Them Up for Failure
Helping them out is cool, but the best gift is teaching them how to manage money, be realistic about their standard of living and learn to stand on their own.
-
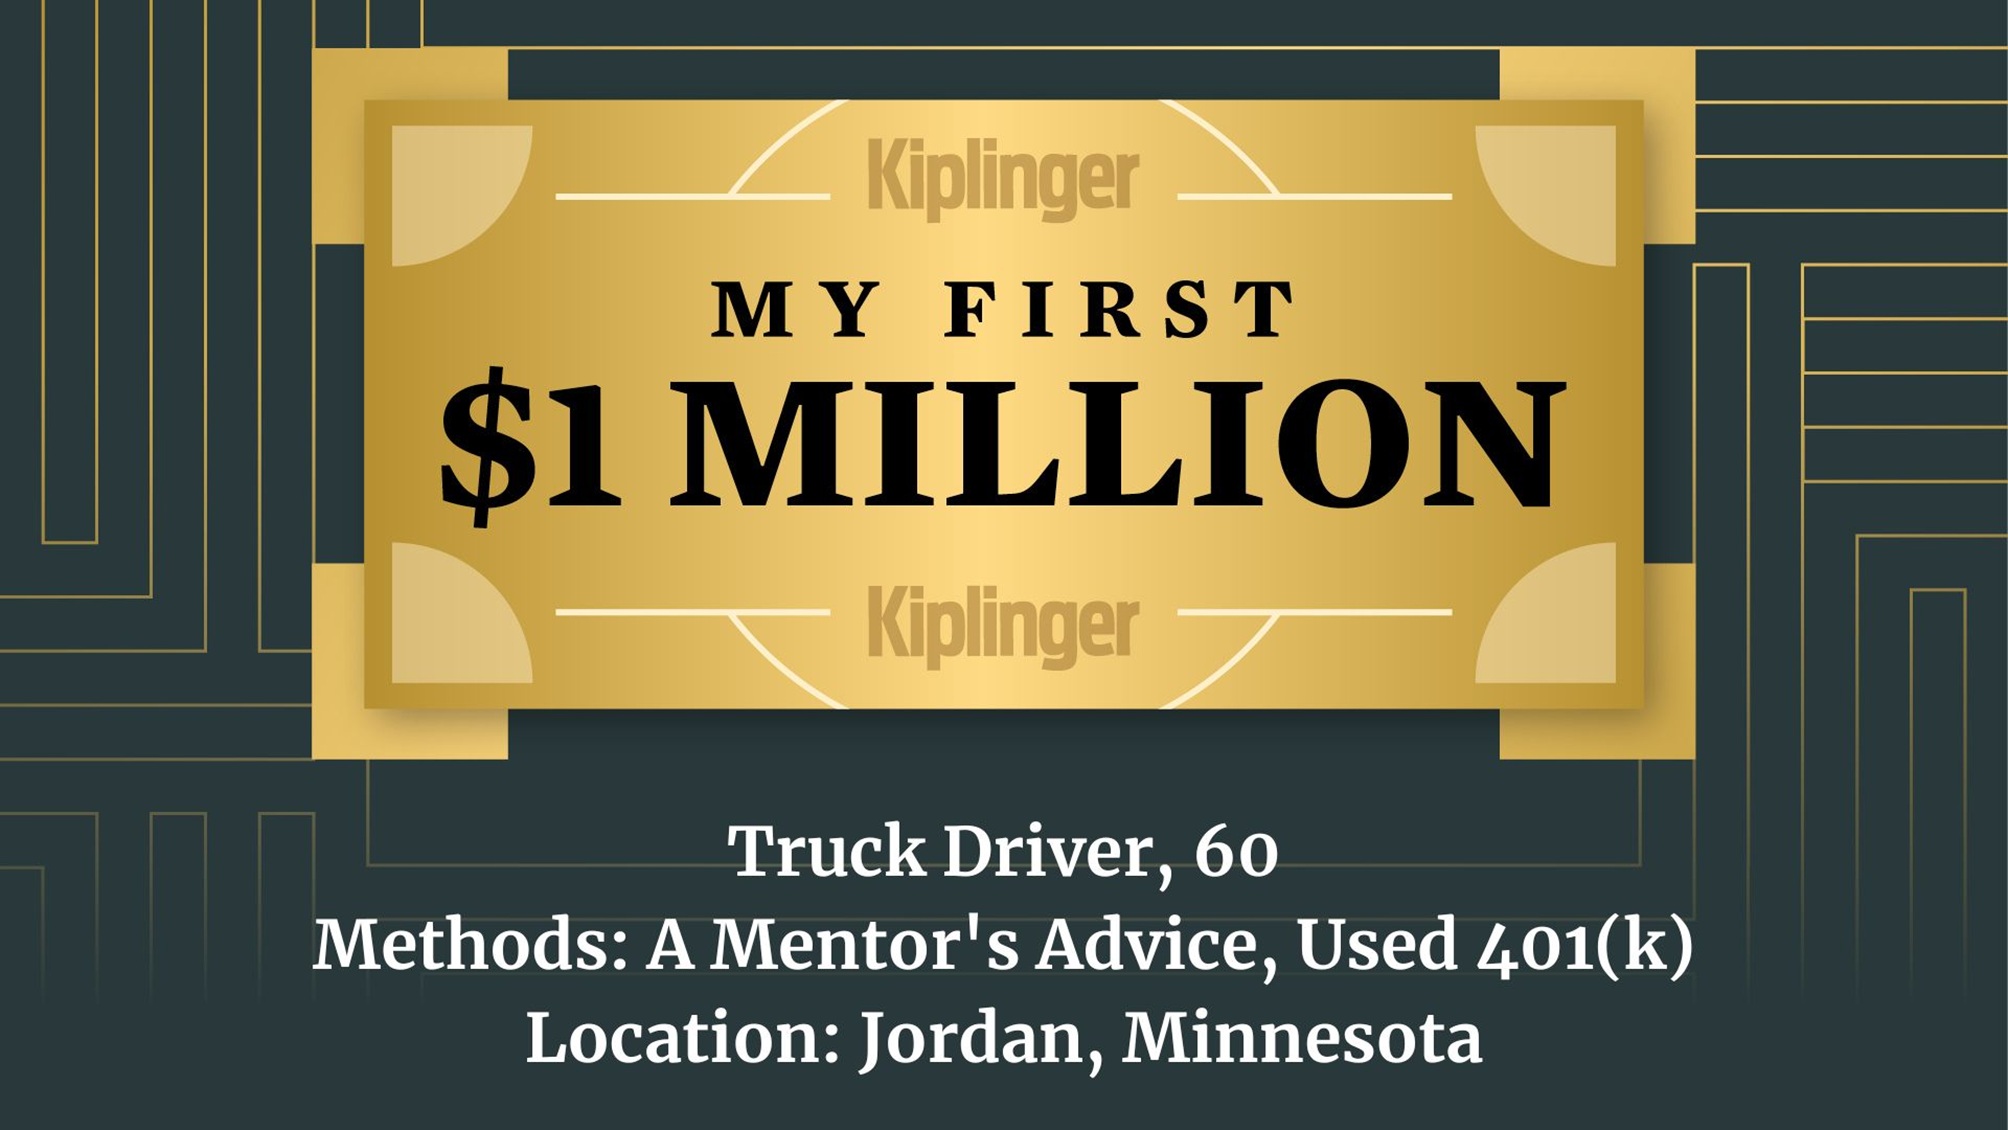 My First $1 Million: Truck Driver, 60, Jordan, Minnesota
"I took $50,000 out of my 401(k) at (age) 40 to buy a business. Three years later, the business was broke, and we were going to be foreclosed on our home."
-
 Would You Rather Retire in Naples, FL, or Palm Springs, CA?
Coastal tradition or desert cool? We break down the real cost — and culture — of retiring in two of America’s most iconic zip codes.
-
 Visa and Mastercard Agree to $167.5 Million ATM Fee Settlement: Do You Qualify?
If you paid a fee to withdraw cash from a non-bank ATM anytime between 2007 and 2026, you could be eligible for a payment from a $167.5 million settlement. Here’s who is eligible and how to file a claim.
-
 5 Ways to Supercharge Your Retirement Savings While You're Still Working
From HSAs to backdoor Roths and even taxable brokerage accounts, there are plenty of ways to boost retirement savings once you've hit your full 401(k) match.
-
 How to Use (and Not to Use) AI for Financial Advice and Investing
AI can't take the place of the human touch when it comes to getting investment advice and planning for your future.
-
 Inherited a Check? Here's What to Do with It Next
Depositing an inheritance check might be trickier than you think. Here are your options and smart strategies to take that gift and build lasting wealth.
-
 Human Capital: The Major Asset (and Invisible Risk) in Your Client's Investment Portfolio
While conventional wisdom views a career as a stable bond, human capital carries unique risks, so a client's job shouldn't always be treated as a safe asset.


